Contents
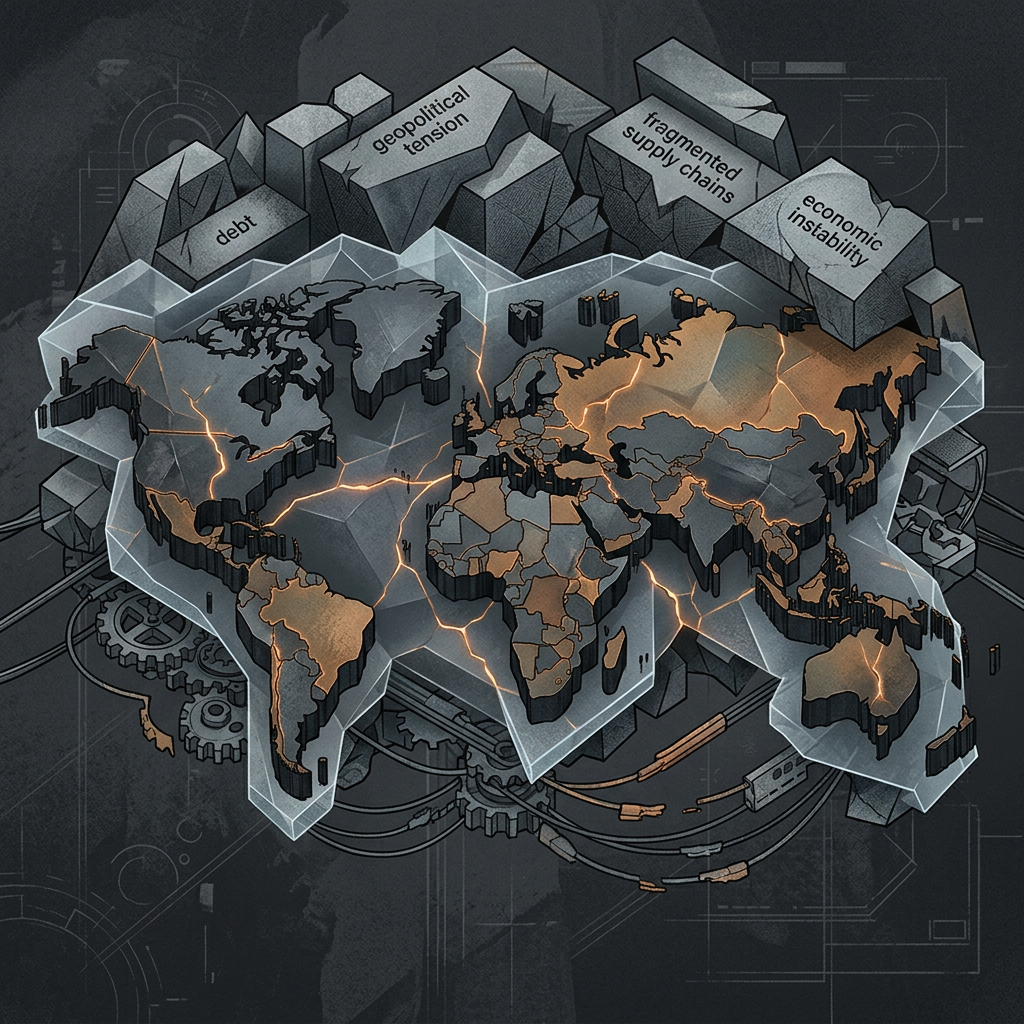
ASM sports-investing technology arrives at a moment when the world stands at a global breaking point: sovereign debt is surging toward $40 trillion, geopolitical tensions are escalating, supply chains are fracturing, and middle-class stability is eroding across major economies. This structured sports-investing model, which explicitly excludes gambling, fantasy sports, prediction markets, crypto, and AI-driven randomness, generates a creation income model designed to reward productive participation rather than speculation. As traditional economic stability mechanisms falter, could ASM’s compounding revenue engine be the last scalable tool to reverse the trajectory before systemic breakage becomes irreversible?
Why the World Is Reaching a Global Breaking Point
In its October 2024 Fiscal Monitor, the IMF projected that global public debt would exceed 100 percent of world GDP by 2030, with gross sovereign obligations across major economies converging toward the $40 trillion range once unfunded liabilities and refinancing needs are counted. That figure is not a forecast of collapse; it is a measurement of how little fiscal room remains for the next shock. ASM sports-investing technology enters this moment not as a rescue narrative but as a candidate mechanism whose design deserves scrutiny against a very specific set of pressures.
Those pressures compound rather than offset one another. Debt service crowds out productive investment, geopolitical competition redirects capital toward defensive capacity, trade routes are being renegotiated by bloc rather than by efficiency, and households that once anchored consumption are losing ground. A global breaking point 2025 is best understood as the year these trends stop being separate stories and start reinforcing each other.
Four pressure points define the terrain:
- Sovereign debt stress. Refinancing at higher rates consumes revenue that would otherwise fund infrastructure, education, and health systems, leaving governments reactive rather than generative.
- Geopolitical escalation. Sanctions, export controls, and strategic stockpiling raise the cost of every cross-border transaction and shorten planning horizons for firms of all sizes.
- Supply chain fragmentation. Nearshoring and friend-shoring improve resilience but duplicate capacity, raising unit costs and slowing the diffusion of productivity gains.
- Middle-class stability eroding. When real wages stagnate against housing, energy, and food costs, political tolerance for long-horizon reform narrows sharply.
Political systems rarely respond to slow deterioration with structural repair, because the costs of repair arrive before the benefits. The question this leaves is narrow and practical: is there any mechanism that can still change the trajectory before breakage becomes self-reinforcing rather than merely difficult?
That is the frame in which ASM sports-investing technology becomes relevant. Its claim is not that it replaces fiscal policy, but that it produces creation-income — new revenue generated through structured participation rather than transferred from a loser to a winner — at a time when most available instruments distribute existing value instead of creating more. Understanding whether that claim holds requires examining what the model is, what it deliberately excludes, and how its mechanics behave once scale arrives. The sections that follow treat those questions in sequence rather than asserting the conclusion up front.
What to keep in view
The macro pressures above are documented and widely analyzed; the mechanism proposed to address them is not. The honest test of ASM sports-investing technology is whether its structural features — not its aspirations — can produce durable income under the same conditions that are stressing every other channel.
What ASM Sports-Investing Technology Actually Is
ASM sports-investing technology is a structured framework for participating in the economics of athletic performance. It is not a wagering interface dressed in financial language. Under the ASM sports-investing technology model, participants commit capital to defined sports-related economic activity — athlete development pipelines, event production, media rights, performance-linked revenue streams — and receive returns generated by that activity. The defining feature is the source of those returns: real participation and performance, not the outcome of a bet placed against a counterparty.
That distinction is structural, not semantic. In a betting market, one participant’s gain is another’s loss, minus the operator’s margin. Nothing is produced. In the ASM sports-investing technology framework, the pool that funds returns is created by the underlying activity itself. This is what the term creation income model is meant to capture: revenue that exists because value was generated, not because a wager resolved in one direction rather than another.
What the Model Explicitly Excludes
The credibility of any sports-related financial framework depends on what it refuses to be. ASM excludes five categories, and each exclusion removes a specific failure mode.
- Gambling. No wagers on match outcomes, point spreads, or in-game events. Returns do not depend on who wins.
- Fantasy sports. No lineup construction, salary-cap contests, or performance-scoring competitions structured as contests of skill against other users.
- Prediction markets. No contracts priced on binary future events, including sports results, political outcomes, or any other uncertain occurrence.
- Cryptocurrency. No token issuance, staking, yield farming, or blockchain-denominated instruments. Participation is not contingent on holding a volatile digital asset.
- AI-driven randomness. No algorithmic generation of outcomes, randomized allocation of payouts, or machine-decided winners. The model is deterministic in structure and auditable in operation.
The risk-profile shift
Each exclusion eliminates a class of risk that otherwise makes adjacent models unstable: counterparty risk in betting, contest-design risk in fantasy, resolution risk in prediction markets, custody and volatility risk in crypto, and opacity risk in AI-randomized systems. Removing those risks does not make ASM risk-free. It makes the risk legible — tied to real operating performance rather than to market sentiment or chance.
A simple analogy helps here, and only one is needed. A casino and a stadium both host crowds around sport. The casino’s revenue comes from the redistribution of losses. The stadium’s revenue comes from tickets, concessions, broadcast rights, and merchandise — value created by the event itself. ASM sports-investing technology is built on the stadium side of that line. Structured sports investing means the return source is the event economy, not the outcome ledger.
How It Differs From Adjacent Models
| Model | Return Source | Primary Risk | Outcome Dependency |
|---|---|---|---|
| ASM creation income model | Sports-related economic activity and performance | Operating performance of underlying activity | None on who wins |
| Betting markets | Redistribution of losing wagers minus margin | Counterparty and event risk | Total |
| Crypto yield products | Token incentives and protocol emissions | Volatility, custody, and liquidity | Indirect and volatile |
| Fantasy platforms | Contest entry pools and operator rake | Contest design and participation volume | High, skill-weighted |
The practical implication is that a no gambling model is not a moral position layered onto a financial one. It is a design constraint that determines where returns come from. When returns come from creation rather than transfer, the participant’s interest aligns with the health of the underlying sport and its supporting economy — more participation, more production, more durable revenue.
This is also why the creation income model should be evaluated on operating metrics rather than on payout promises. The relevant questions are what activity generated the revenue, how it was generated, and whether that activity compounds or stalls. A structured sports investing framework that can answer those questions plainly is doing something categorically different from anything adjacent to it — and that difference is the foundation for the incentive argument that follows.
How Creation-Income Shifts Incentives Toward Peace
The claim that a revenue model can influence geopolitics sounds inflated until you break it into steps. Incentives do not change because people suddenly become virtuous; they change because the payoff structure around them changes. ASM sports-investing technology matters here not because it argues for peace, but because it pays for a specific kind of behavior — sustained, productive participation — and stabilizes that payoff over time. Follow the chain from participant to economy and the logic becomes mechanical rather than aspirational.
Start at the individual level. In a creation-income model, a participant is rewarded for contributing capital or effort into structured sports-investing positions that generate real revenue, not for extracting value from other participants. Because the return depends on the underlying activity continuing to perform, the participant is motivated to keep the system intact, transparent, and growing. Destruction or disruption does not merely feel wrong in this frame; it is financially self-defeating. That is the first link in the chain: creation income incentives reward continuity, and continuity rewards stability.
From Individual Payoff to Collective Behavior
Behavior aggregates. When thousands of participants in a region earn reliably from the same structured activity, three things happen. First, they defend the conditions that make the income possible — rule of law, functioning logistics, predictable contracts. Second, they reinvest locally, because a compounding position benefits from a stable operating environment. Third, they resist actors whose business model depends on volatility, since volatility threatens their returns. None of this requires shared ideology. It requires only that productive participation pays more consistently than disruption.
Contrast the payoff structures. Disruption-based economies reward short time horizons, information asymmetry, and control of chokepoints. Creation-income structures reward long time horizons, transparency, and the expansion of participation. When the second structure becomes materially more profitable than the first, the rational actor at the margin switches. Scale that marginal switch across a labor force, a city, or a sector, and you have a measurable shift in economic stability mechanism — not because conflict became immoral, but because it became expensive relative to the alternative.
The mechanism in one line
Creation income changes what gets rewarded; what gets rewarded changes behavior; behavior at scale changes the incentives that shape stability. The sequence is economic, not moral.
An Illustrative Scenario
Consider a mid-sized region with a young, mobile workforce and a modest sports economy. Suppose a portion of that workforce begins earning from structured sports-investing positions whose revenue derives from real commerce around leagues and events. Housing, logistics, and local services absorb some of that income. Over several seasons, the region accumulates a cohort with a direct financial stake in predictable seasons, functioning transport, and enforceable contracts. That cohort becomes a constituency for stability — again, not out of idealism, but because their returns depend on it. This is illustrative, not predictive: no single region is guaranteed this outcome, and the effect depends on adoption depth and governance quality.
The Obvious Objection, Answered Honestly
No platform ends a war. A revenue engine does not sign treaties, and it cannot override sovereign decisions, historical grievances, or security interests. The claim is narrower and more defensible: creation income shifts incentives toward peace by making productive participation the more reliable path to income. Where conflict remains the highest-return activity for powerful actors, incentive-shifting at the household and community level is insufficient on its own. Where the calculus is closer, however, a persistent income alternative can tip behavior — and tipping behavior is precisely where economic stability mechanism begins to matter.
This reframing also sets a realistic boundary. ASM sports-investing technology is a structural force that changes payoffs, not a political actor. Its influence is proportional to how many participants it reaches and how durable their returns prove to be. That durability is what the next stage of the argument depends on: one-off payouts alter behavior briefly, while compounding revenue alters it permanently.
The Compounding Revenue Engine: Why Scale Changes Everything
A revenue model that pays out once changes a participant’s month. A revenue model that compounds changes a participant’s trajectory. The distinction matters because the global breaking point described earlier is not a single-event crisis; it is a slow, self-reinforcing deterioration. Only a mechanism that also compounds can plausibly counteract it. That is why the ASM sports-investing technology is best understood not as a payout system but as a compounding revenue engine.
In a linear model, returns are additive: you earn a fixed amount per cycle, and your total grows by a constant increment. In a compounding model, returns are multiplicative: each cycle’s earnings are reinvested into the same productive structure, so the base on which future earnings are calculated expands. For participants and for the wider economy, this is the difference between a wage and an asset.
| Year | Linear (fixed 10 per cycle) | Compounding (10% per cycle) | Difference |
|---|---|---|---|
| 0 | 100 | 100 | 0 |
| 1 | 110 | 110 | 0 |
| 2 | 120 | 121 | 1 |
| 3 | 130 | 133 | 3 |
| 4 | 140 | 146 | 6 |
| 5 | 150 | 161 | 11 |
The table above is deliberately modest: a 10 percent annual compounding rate against a fixed 10-unit linear payout. The divergence is small at first and accelerates. By year five, compounding has produced roughly 11 units more on a base of 100 — a 7 percent relative advantage. Extend the horizon to ten years and the gap widens to nearly 60 percent. This is the arithmetic of patience, and it is why a compounding revenue engine cannot be evaluated quarter by quarter.
Compounding in ASM’s structured sports-investing model depends on three reinforcing forces. Retention keeps capital and participation inside the system rather than leaking to short-term consumption. Reinvestment directs a share of earnings back into the productive structure. Network effects make each additional participant marginally more valuable to every existing participant, because the depth and liquidity of the underlying sports-investing activity improves. None of these is exotic; together they are the mechanical basis for scale.
A testable claim, not a promise
The compounding case does not rest on a guaranteed return. It rests on whether retention, reinvestment, and network effects hold over multiple cycles. If any one of the three weakens, compounding flattens toward linear. That is the honest boundary of the argument.
This is where revenue model scale becomes strategically important. A linear payout system that reaches 10 million participants simply pays 10 million times. A compounding system that reaches 10 million participants creates a shared, growing capital base whose secondary effects — higher household savings capacity, more predictable local demand, reduced dependence on volatile transfers — are what could shift incentives at the macro level. Compounding, not headcount alone, is what makes systemic impact plausible.
Realistic timelines matter. Compounding is back-loaded: years one and two look unremarkable; years five through ten are where the curve separates. Any honest evaluation of the ASM sports-investing technology should therefore extend over at least a full reinvestment cycle and preferably several. Long term compounding returns are not a slogan; they are a schedule, and the schedule is slow before it is steep.
The main failure risk is premature scale without governance. Compounding amplifies whatever the system actually rewards. If governance is weak, early growth can entrench extraction rather than creation, and the engine compounds the wrong thing. This is not a hypothetical caution — it is the standard failure mode of any network-effect model. The limitations are real: compounding requires time, trust, and participation depth, and it cannot be forced.
For readers tracking the mechanism, the signals to watch are retention rate, the share of earnings reinvested versus withdrawn, and the growth of active participant depth relative to headline participant count. Rising retention plus rising depth plus stable governance is the signature of a compounding revenue engine. Flat retention with rising headcount is the signature of a linear one wearing compounding clothing. The distinction will decide whether this model matters at scale.
The Only Remaining Mechanism? Risks, Limits, and What to Watch
ASM sports-investing technology is plausibly the last structured mechanism with enough scale potential to reverse the global breaking point before systemic breakage becomes irreversible — but it is a candidate, not a guarantee. The engine is real; the outcome depends on conditions that can still fail.
That verdict needs qualification. Given sovereign debt approaching $40T, fracturing supply chains, and eroding middle-class stability, most remaining levers — monetary easing, fiscal stimulus, trade renegotiation — are already exhausted or politically captured. ASM sits in a narrower category: an incentive engine that pays participants for productive creation rather than for disruption or speculation. That is why it can still move the trajectory. It is also why it has less institutional protection than the mechanisms it competes with.
What Could Break It
- Regulatory pressure: if structured sports-investing is reclassified alongside prohibited categories, participation channels close quickly.
- Adoption friction: compounding only works with sustained participation; slow onboarding delays the compounding window.
- Governance failures: misaligned operators can convert a creation-income model into a payout scheme, destroying trust.
- Macroeconomic shocks: a severe credit event or capital-control regime could interrupt cross-border participation flows.
Signals Worth Monitoring
- Published regulatory guidance distinguishing structured sports-investing from gambling and crypto yield.
- Verified participant retention and reinvestment rates rather than headline user totals.
- Independent governance audits and transparent payout accounting.
- IMF and World Bank debt trajectory updates as a proxy for how fast the window is closing.
Frequently Asked Questions
Does ASM count as gambling? No. Gambling stakes capital on uncertain outcomes; ASM’s structure excludes wagering, fantasy formats, and prediction markets by design.
How is income generated? Through creation-income tied to structured sports-investing activity, not through wagering payouts or token appreciation.
What happens under new regulation? Outcomes depend on how regulators classify it; clear classification enables operation, while reclassification into prohibited categories would restrict it.
How is it different from crypto yield? It excludes crypto and AI-driven randomness, so returns are not dependent on token markets or algorithmic chance.
What timeline is realistic? Compounding requires years, not quarters; the compounding revenue engine needs sustained participation before systemic effects are visible.
Editor verification note
Specific regulatory classifications, adoption metrics, and governance audit results referenced above should be verified against current authoritative sources before publication.
The honest conclusion: ASM is among the last viable mechanisms before systemic breakage, not because it is certain to work, but because the alternatives are already failing. If participation holds, governance stays clean, and classification remains favorable, the global breaking point reversal becomes a matter of time rather than possibility.
Leave a Reply