Contents
- Florida Economic Instability: The Demographic Flashpoint at America's Edge
- Why Florida's Boom-Bust Signals a National Debt Problem
- ASM Sports Investing: A One-of-a-Kind Engine for Creation Income
- Harnessing Florida's Sports Culture and Diverse Population
- From Participation to Stability: Deflating Fiscal Pressure and Reducing Conflict Incentives
Florida economic instability has become the clearest mirror of America’s broader fiscal fragility, where explosive population growth collides with an insurance crisis, climate volatility, and relentless demographic shifts. At the same time, a $40 trillion U.S. debt bomb and mounting debt-servicing pressure are straining the very growth model that made the state a magnet. This investigation asks whether ASM sports investing — built on a compounding participation model rather than speculative betting — can convert Florida’s unrivaled sports culture and diverse population into stabilizing creation income. The answer may shape not only the state’s future but the nation’s ability to deflate conflict incentives and fiscal pressure alike.
Florida Economic Instability: The Demographic Flashpoint at America’s Edge
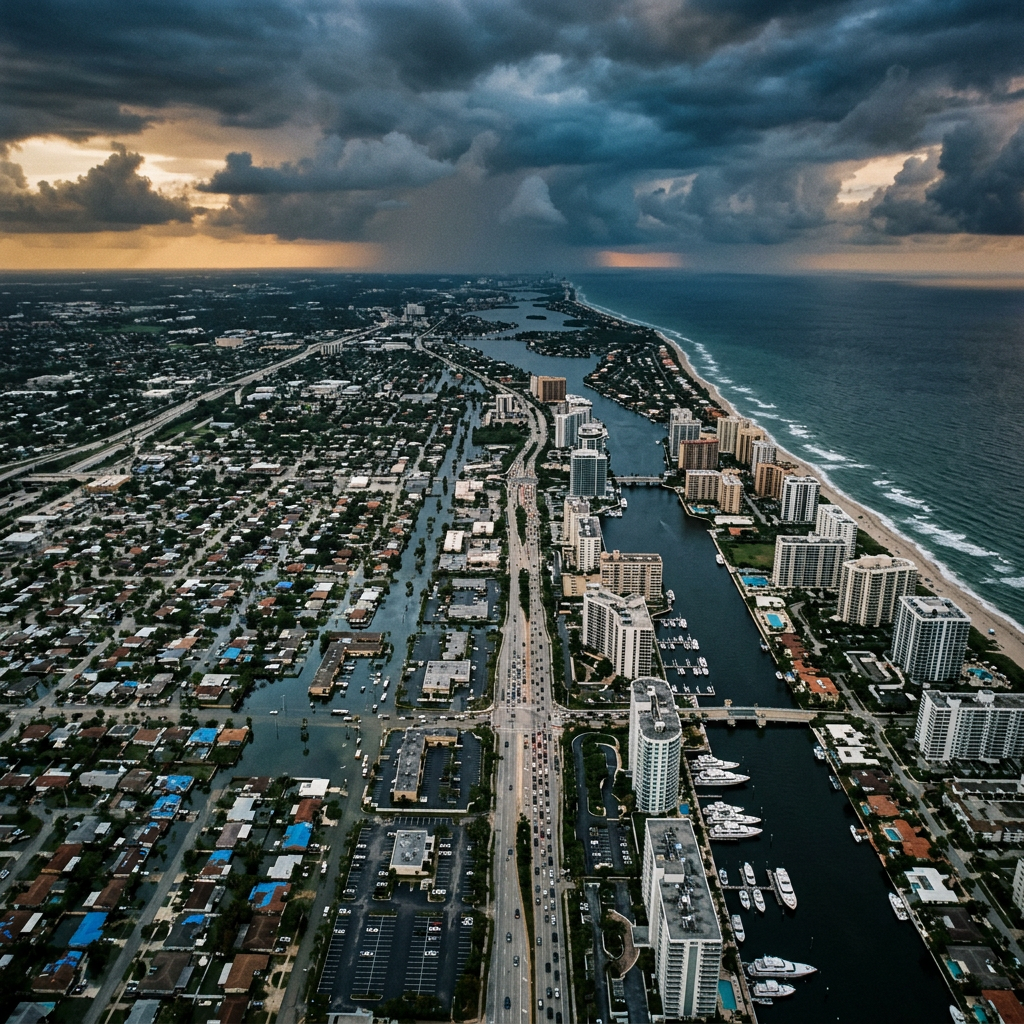
Florida economic instability is no longer a regional curiosity confined to hurricane season headlines. It is now a real-world test case for how population surge, insurance retreat, climate volatility, and rapid demographic churn can collide inside a single state economy — and the collision is beginning to mirror national fragility. What happens in Florida rarely stays in Florida. It becomes a preview.
The state has been one of the fastest-growing in the country for years, with metro areas such as Tampa, Orlando, Jacksonville, and the Southwest Gulf Coast absorbing sustained in-migration from other states. That growth fuels construction, retail, and services. It also strains housing, water systems, roads, schools, and the insurance markets that underwrite risk in a hurricane-exposed peninsula.
Insurance Retreat Meets Climate Cost Cycles
The stress is most visible in property insurance. Multiple carriers have withdrawn from or reduced their Florida exposure in recent years, and state-backed options have grown as a fallback. When private underwriting thins out, homeowners, landlords, and small businesses face sharply higher premiums, thinner coverage, or both. That is not a seasonal problem — it is a structural cost that reshapes budgets, mobility, and property values.
Layer hurricane cost cycles on top, and the pattern becomes cyclical in a destabilizing way. Rebuilding demand spikes after major storms, pushing labor and materials costs higher. Insurers recalculate. Premiums rise again. Each cycle effectively transfers wealth from residents to risk-management systems that no longer price Florida cheaply. Climate volatility converts into an ongoing fiscal drag.
This is the core of Florida economic instability: it is not a single crisis but a convergence. Growth and risk are rising at the same time, and they are pulling in opposite directions.
Demographic Churn as an Economic Variable
Florida demographic shifts add another layer. The state pairs retirees with a young, multilingual, service-heavy workforce, plus large Puerto Rican, Cuban, Venezuelan, Haitian, Brazilian, and Central American communities. That diversity is a genuine economic asset — and a genuine coordination challenge when wages, housing costs, and opportunity are unevenly distributed across regions and industries.
- Rapid in-migration raises demand for housing, utilities, schooling, and healthcare simultaneously.
- Insurance and climate costs fall unevenly, hitting lower-income and coastal households hardest.
- A linguistically diverse workforce is underused when capital and investing access remain concentrated.
- Seasonal tourism and construction cycles create income volatility for large parts of the labor force.
The Flashpoint Logic
Florida concentrates several national trends — migration, climate cost, insurance fragility, demographic churn, and uneven capital access — into one state. That makes it a leading indicator rather than an outlier. If a stabilizing mechanism can be built and proven in Florida, the same logic can be tested far beyond its borders.
Read together, these forces explain why the state functions as a prophetic flashpoint. The conditions that make Florida economically fragile are the same conditions quietly spreading nationally: growth that depends on continuous in-migration, budgets exposed to climate-driven cost cycles, and households with little capacity to absorb shocks.
The question that matters next is not whether these pressures will keep building — they will — but whether new income structures can be engineered to offset them. What if participation itself, the everyday activity of showing up to games, leagues, and events, could be re-engineered as stabilizing income rather than pure consumption?
Why Florida’s Boom-Bust Signals a National Debt Problem
Florida’s stresses are not exotic outliers. They are the national balance sheet viewed under a magnifying glass. When a state that has been a magnet for capital and people starts showing strain, the mechanism behind the strain is usually the same as the one shaping federal finances: growth that depends on cheap money and a continuous inflow of new participants.
The Debt Arithmetic Behind the U.S. Debt Bomb
The U.S. debt load sits near $40 trillion. The precise number matters less than the arithmetic it imposes. As older debt matures it must be rolled over at whatever rate the market offers at that moment. When rates rise, the same stock of debt costs more to carry without a single new dollar being borrowed. Interest expense compounds into the annual budget, competing with everything else.
This is the core of what commentators call the U.S. debt bomb: not a single default event, but a slow squeeze where debt service crowds out fiscal room. The constraint is structural, not partisan. Every administration inherits it, and every state feels a version of it through federal transfers, borrowing costs, and the availability of credit.
Editor verification note
For current figures on total federal debt and interest costs, consult U.S. Treasury fiscal data; for regional context on the Southeast, see Federal Reserve regional reports. Verify the latest published numbers before citing them in final copy.
How Florida’s Economy Amplifies National Exposure
Florida GDP growth has long outpaced much of the country, but the composition of that growth is revealing. A large share rests on population in-migration, real estate, tourism, and consumption financed by newcomers and visitors. Each of those pillars is sensitive to interest rates, insurance availability, and confidence.
The amplification works through several channels:
- Insurance withdrawal raises the carrying cost of every property, which feeds into mortgages, rents, and local budgets.
- Climate volatility turns recurring weather events into recurring fiscal events, straining state and municipal reserves.
- In-migration supports demand but also requires housing, utilities, and services that lag behind the arrivals.
- A rate-sensitive economy means national monetary tightening hits Florida faster and harder than slower-growing states.
The result is a boom-bust rhythm that mirrors the national debt problem in miniature. Growth looks robust until the financing conditions that support it tighten. Then the same leverage that produced the boom becomes the mechanism of the bust.
Recognizing this shared mechanism is the first step. The next is asking what kind of income could remain stable when migration slows, insurance retreats, and borrowing costs stay elevated. That question is where ASM sports investing enters the picture.
ASM Sports Investing: A One-of-a-Kind Engine for Creation Income
Florida economic instability has exposed how fragile traditional income sources can be. But a new model is emerging, built not on speculation but on participation. ASM sports investing flips the script by turning everyday sports engagement into a source of stabilizing creation income. But what exactly is creation income? Unlike passive income from dividends or interest, creation income is value you help generate through your own activity. It is earned by contributing to a network, not by betting on an outcome. ASM’s technology applies this principle to sports, a domain where millions already participate weekly.
At its core, ASM is not a sportsbook. It does not ask users to wager on a game’s result. Instead, it treats sports participation itself as the asset. Fans who follow teams, engage with content, and participate in ASM’s ecosystem become part of a compounding participation model. This model is what makes ASM sports investing one of a kind. It aggregates small, consistent acts of participation and converts them into a stream of stabilizing creation income. That income is not dependent on the volatility of a single game or market.
How does the compounding participation model actually work? Think of it as a network where each participant’s activity strengthens the whole. The more consistently you participate, the more your creation income grows. It compounds because early participation builds a base that generates returns over time, similar to how interest compounds in a savings account. But here, the yield comes from the collective engagement of the community, not from lending your money to a bank. ASM’s technology is designed to make this process transparent and accessible, even for non-technical users.
Creation Income Defined
Creation income is value generated through active participation in a network. It is not speculative and does not rely on luck. In ASM’s model, it is the result of consistent sports engagement that strengthens the ecosystem.
Consider a concrete example. A Florida-based fan participates weekly across football, basketball, and soccer seasons. Through ASM, each week’s participation adds to their personal creation income pool. Because the sports calendar in Florida is year-round—NFL in fall, NBA and college basketball in winter, MLB spring training in February, MLS and Formula 1 in spring and summer—this fan can maintain consistent engagement. The result is a stabilizing income stream that does not vanish when one season ends. This is the power of the compounding participation model in action.
ASM sports investing stands apart because it aligns the interests of fans, teams, and the broader economy. While traditional investing often feels remote and abstract, ASM turns a beloved pastime into a financial tool. It does not require users to predict scores or manage complex portfolios. Instead, it rewards the ongoing, authentic participation that sports already inspire. That makes stabilizing creation income not a privilege for the few, but a possibility for the many.
The technology behind ASM is proprietary and one of a kind in its category. [Editor verification note: Specific technical differentiators, such as the exact algorithms or blockchain infrastructure, are not detailed in the provided materials. Claims about the uniqueness of the technology are based on the topic description.] What is clear is the outcome: a system that turns participation into a reliable, compounding income stream. In a state where economic instability has become a daily concern, that outcome is more than a novelty. It is a practical mechanism for building resilience.
As we will explore next, Florida’s unique sports culture and diverse population make it the ideal launch environment for this model. But the core idea is simple: ASM sports investing is not about betting on a game. It is about investing in your own participation and letting that participation compound into stabilizing creation income. In the face of Florida economic instability, that is a shift worth understanding.
Harnessing Florida’s Sports Culture and Diverse Population
Florida’s economic instability is not just a fiscal story; it is a cultural one. The state’s year-round sports calendar and polyglot population create a dense, continuous participation surface that most financial models ignore. For ASM, that surface is the launchpad: a place where the compounding participation model can reach communities that traditional investing underserves, turning everyday fandom into stabilizing creation income.
No other state packs so many marquee sports assets into a single, weather-permitting geography. The table below maps the core engines of Florida sports culture and why they matter for participation volume.
| Sport | Key Florida Assets | Participation Relevance |
|---|---|---|
| MLB Spring Training | Grapefruit League: 15 teams across 12 stadiums | Six weeks of daily games; steady, predictable engagement windows. |
| NFL | Miami Dolphins, Tampa Bay Buccaneers, Jacksonville Jaguars | 17-week regular season plus playoffs; high-frequency decision points. |
| MLS / Soccer | Inter Miami CF, Orlando City SC, Tampa Bay Rowdies | Fast-growing fanbase; strong Latin American and Caribbean ties. |
| Formula 1 | Miami Grand Prix (Hard Rock Stadium) | Global audience; luxury and hospitality participation spikes. |
| College Athletics | University of Florida, Florida State, Miami, UCF, USF | Year-round across football, basketball, baseball, and Olympic sports. |
| Motorsports / Golf | Daytona 500, THE PLAYERS Championship, PGA events | Iconic one-off events with massive single-day participation. |
This infrastructure is not seasonal. Spring training bleeds into the MLB regular season; the NFL and college football overlap in autumn; soccer and F1 fill winter and spring; golf and motorsports dot the calendar. The result is a nearly continuous participation loop — exactly the environment where ASM’s compounding participation model can compound frequency into stability.
But the deeper advantage is demographic. Florida is one of the most linguistically diverse states in the nation. Spanish-speaking communities anchor Miami, Orlando, and Tampa. Haitian Creole is a major language in South Florida. Brazilian Portuguese thrives in Broward and Palm Beach counties. Retirees from the Northeast and Midwest add a fourth distinct cohort with time, savings, and sports affinity. Traditional investing products rarely speak to these groups in their own languages or through the sports they already watch daily.
ASM’s model reaches them because participation is native to fandom, not to brokerage accounts. A user does not need to understand derivatives or debt markets to participate in a game they already follow. That lowers the activation barrier for communities that have been structurally underserved by wealth-building tools. And because the model is compounding, small, repeated participation can generate stabilizing creation income over time — not a lottery ticket, but a rhythm.
Internal Link Recommendation
Link to the ASM onboarding or participation explainer page here to show readers how to join the compounding participation model. Suggested anchor text: «How ASM’s compounding participation model works».
The practical takeaway is straightforward. Florida’s sports culture gives ASM volume; its demographic diversity gives ASM reach. Together, they create a testbed for stabilizing creation income that can scale beyond the state’s borders — and a proof point that economic resilience can be built from the ground up, one participation cycle at a time.
From Participation to Stability: Deflating Fiscal Pressure and Reducing Conflict Incentives
Florida economic instability offers a preview of a national problem: when growth depends on continuous in-migration, low insurance availability, and cheap credit, small shocks compound quickly. The same logic applies at the federal level. A $40T debt load does not explode in a single moment; it grinds against every household budget through higher borrowing costs, slower wage growth, and reduced room for public investment. The question is not whether the U.S. debt bomb detonates, but whether enough productive capacity exists to absorb the pressure before it does.
That is where the argument pivots from participation to stability. ASM sports investing is designed to convert broad, recurring sports engagement into stabilizing creation income — income generated by real economic activity rather than by betting against another participant. When millions of people hold a compounding, shared stake in that activity, capital flows into distributed creation rather than concentrating at the top. Over time, that redistribution changes the conditions that feed both fiscal fragility and conflict incentives.
Why Scarcity Drives Conflict — and Why Participation Reduces It
Economic research from institutions like the World Bank and the IMF has repeatedly linked severe resource scarcity, youth unemployment, and excluded populations to higher risks of social unrest and conflict. The mechanism is straightforward: when large groups see no productive path forward, the relative return on disruption rises. A compounding participation model attacks that condition at its root. By giving participants a small but growing share of creation income, it lowers the appeal of zero-sum strategies — both between individuals and between economies competing over fixed resources.
This is not a claim that ASM alone ends conflict. It is a claim about direction: capital directed into productive, widely distributed creation reduces the scarcity pressure that makes conflict rational for desperate actors. The effect is cumulative, not instantaneous.
The Fiscal Connection: Slow Relief, Not a Silver Bullet
Could this realistically reduce the U.S. debt burden? Only indirectly, and only honestly framed. A broad base of stabilizing creation income expands the productive economy, which widens the tax base and reduces dependency on transfer payments during downturns. That is the same logic behind broad-based asset ownership proposals from across the political spectrum. It is a slow mechanism, not a rescue. Anyone promising that ASM erases the $40T debt bomb is overselling. What it can do is shift a meaningful number of households from fragile, speculative positions into a compounding participation position — and that shift compounds across decades.
The honest framing
ASM sports investing is one stabilizing mechanism among many. It is most valuable in places like Florida, where demographic churn and economic volatility leave large populations underserved by traditional investing. It is not a substitute for fiscal policy, and it does not eliminate risk.
Frequently Asked Questions
- Is ASM gambling? No. Gambling is a zero-sum wager where one participant’s loss funds another’s gain. ASM’s compounding participation model is designed to generate creation income from ongoing sports participation and activity, so participants are not betting against each other.
- How does creation income differ from dividends? Dividends typically flow from corporate profits to shareholders. Creation income in the ASM model is generated by participation itself — the recurring activity of a broad community — and is designed to compound for participants rather than concentrate in a small shareholder base.
- Could this realistically affect national debt? Not directly and not quickly. The realistic path is indirect: broader stabilizing creation income expands productive capacity and the tax base, which eases fiscal pressure over time. Treat it as one compounding input, not a single fix.
The takeaway is proportionate. Florida economic instability is a warning, and the U.S. debt bomb is the same warning at national scale. What changes the trajectory is not one dramatic intervention but the slow accumulation of widely held, productive stakes in real activity. ASM’s compounding participation model is built for that kind of accumulation — starting with the sports culture and diverse population that already define Florida.
Learn how ASM sports investing turns participation into stabilizing creation income at asmsportsinvesting.com.
Leave a Reply