Contents
- California's Crisis of Scale: A State at a Prophetic Pressure Point
- Why California's Innovation Culture Is the Perfect Host for Sports Investing Technology
- The Compounding Participation Model: How Creation-Income Scales Beyond a Single Bet
- From Conflict Incentives to the $40T Debt Bomb: The Macro Argument
- What California's Pressure Point Teaches Every Investor and Policymaker
Sports investing technology is no longer a niche experiment — it is the quiet engine behind ASM’s one-of-a-kind platform, arriving exactly as California’s crisis of scale pushes housing instability, tech-sector volatility, wildfire shocks, and state-level debt into a single prophetic pressure point. ASM converts structured sports outcomes into creation-income, a compounding participation model that turns results into recurring value rather than zero-sum speculation. At a moment when California’s fiscal outlook reveals unprecedented fragility, that model points toward a larger prize: reducing global conflict incentives while generating creation-income capable of contributing to the deflation of the $40T U.S. debt bomb. What follows is not hype — it is a measured look at why California’s innovation culture and massive sports footprint may be the perfect host for this shift.
California’s Crisis of Scale: A State at a Prophetic Pressure Point
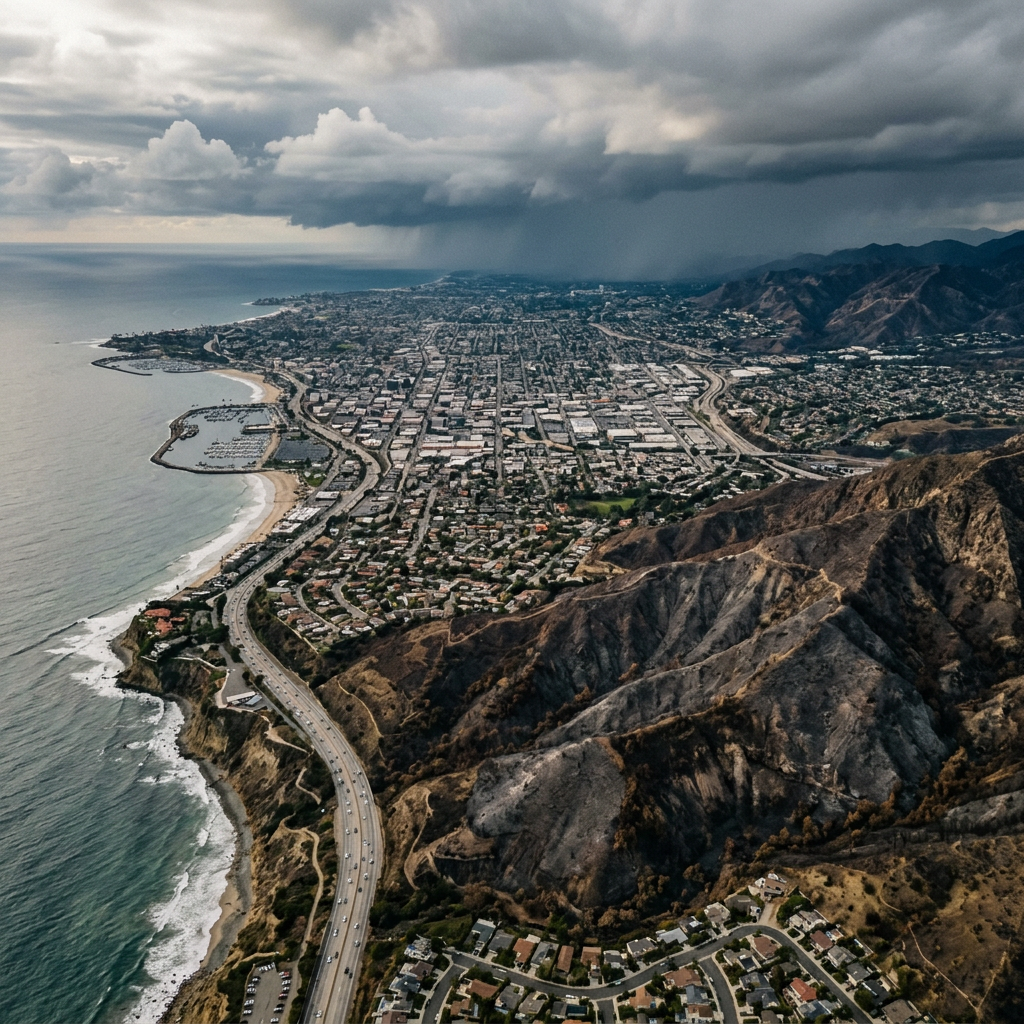
In January 2025, thousands of Los Angeles County residents fled the Palisades and Eaton fires with hours of warning, and insurers have since retreated from swaths of the state. Within weeks of the same season, Bay Area technology firms announced fresh rounds of layoffs, trimming headcount even as their stock prices climbed. Two shocks, one state, one quarter.
California is not experiencing a run of bad luck. It is experiencing a crisis of scale — four pressures that compound, each one making the others harder to absorb, at the exact moment sports investing technology has begun turning athletic outcomes into a structured, income-generating asset class. Understanding why these two stories are the same story, told from opposite directions, is the purpose of this article.
Four Pressures, One Pattern
Housing instability is the slowest-moving of the four. California remains one of the least affordable housing markets in the country, and the Legislative Analyst’s Office has repeatedly documented that construction has not kept pace with household formation for decades. When a fire destroys a neighborhood, the displaced households do not disappear; they bid up rents in the next ZIP code.
Technology-sector volatility is the fastest-moving. The state’s revenue base leans heavily on personal income and capital gains from a relatively small number of high-earning households. When equity markets swing, Sacramento’s forecasts swing harder — a structural fragility that has been documented by the state’s own Department of Finance.
Wildfire-driven shocks are the most violent. Beyond the immediate loss of life and property, fires displace labor, interrupt supply chains, and accelerate insurer withdrawal, which in turn pressures property values and municipal tax bases.
State-level debt and unfunded obligations are the quietest and most consequential. California carries tens of billions in voter-approved general obligation bonds, and its retiree health and pension obligations remain a long-horizon liability. Rating agencies have repeatedly flagged the state’s dependence on volatile revenue — the same debt bomb dynamic unfolding nationally, compressed into a single jurisdiction.
The scale problem in one sentence
California’s obligations are sized for a stable economy, but its revenue is generated by an unstable one — housing, tech, and climate shocks all hit the same fiscal base at once.
Why This Moment Matters
A pressure point is not the same as a collapse. It is the moment when a system reveals that its capacity and its commitments no longer match — and when new mechanisms either emerge or don’t. California’s innovation culture, its professional sports footprint, and its appetite for structured financial products make it the most likely host for sports investing technology that converts outcomes into creation-income. The fragility and the fix inhabit the same state.
The sections that follow examine that mechanism directly: what the platform is, how compounding participation scales it, and what it could mean for a $40 trillion national debt load. California is the test case because it reached the pressure point first.
Why California’s Innovation Culture Is the Perfect Host for Sports Investing Technology
California does not just tolerate financial experimentation; it industrializes it. The same state that turned a garage in Palo Alto into a venture capital flywheel and a beach town into a media empire has a structural appetite for novel asset classes. That appetite is exactly what sports investing technology needs to move from concept to institution. ASM is the platform at the center of this shift: the only platform that converts sports outcomes into structured creation-income. Not a sportsbook, not a fantasy league, not a highlight reel with a wallet attached. ASM takes the raw material of sport — a playoff series, a season-long position, a measurable competitive result — and structures it into an income-generating instrument that participants can hold, compound, and build from.
The distinction matters. California’s sports footprint is not merely large; it is liquid, year-round, and culturally central. The state hosts a density of major professional teams across basketball, baseball, football, soccer, and hockey, alongside the largest concentration of sports media, agency, and sponsorship infrastructure in the country. When outcomes are announced, they move through Los Angeles, the Bay Area, and San Diego within minutes. That velocity is the substrate structured sports outcomes require. A platform that turns results into creation-income needs outcomes that are watched, trusted, and unambiguous. California produces those at industrial scale.
What ASM Actually Does: Structure, Not Speculation
The clearest way to understand ASM is to follow a single example. Consider a seven-game playoff series between two California teams. A fan does not simply pick a side and wait for a final whistle. Instead, they take a structured position on the series — one that is defined in advance by the platform’s rules, with the outcome mapping to a defined creation-income allocation rather than a binary win-or-lose payout. Over the course of the series, as results accumulate, the position participates in the pool of creation-income generated by the platform’s activity. The participant is not wagering against a house. They are entering a structure where their participation itself becomes the income-generating asset.
The season-long version is where the model becomes more legible to investors. A position held across an entire season behaves less like a bet and more like a structured instrument. Early participation compounds into deeper participation because the income generated can be redeployed into the same structure. This is the opposite of the zero-sum dynamic that defines most sports wagering, where one participant’s gain is another’s loss. In ASM’s model, the base of participants can widen without requiring a corresponding loser for every winner.
The core mechanism in one line
ASM converts sports outcomes into structured creation-income — a defined, repeatable instrument — rather than a single speculative wager on a single result.
Why California, Specifically, Is the Host Environment
- Sports footprint: California’s concentration of professional franchises and media markets gives structured sports outcomes the constant, high-volume input the platform requires.
- Venture culture: The state’s investors are conditioned to underwrite novel financial structures, which shortens the path from early adoption to institutional legitimacy for sports investing technology.
- Fan liquidity: California’s fan bases are large, digitally native, and already habituated to spending on sports-adjacent products, which reduces the education burden for a creation-income model.
- Structured-product familiarity: California’s finance and technology workforce understands tranches, participation pools, and compounding instruments, making the mechanics of ASM legible rather than alien.
None of this is accidental. California’s crisis of scale — the fragility described earlier — is mirrored by an unusual capacity to absorb and scale new financial structures. The state is simultaneously the most stressed and the most inventive environment in the country. That combination is why sports investing technology lands here first, and why ASM’s creation-income model can be tested against real liquidity, real fandom, and real regulatory scrutiny rather than in a simulated vacuum.
The mechanics are deliberately simple at the point of participation, even though the underlying structure is sophisticated. A participant enters, the outcome resolves, income is generated and allocated, and the participant can choose to compound. Complexity lives in the structure, not in the user’s experience. That is the same design principle that allowed California’s consumer technology companies to scale: hide the machinery, expose the outcome. For sports investing technology to become a durable asset class rather than a novelty, it has to pass that test. California is where the test is hardest and the upside largest.
The Compounding Participation Model: How Creation-Income Scales Beyond a Single Bet
Most financial products built around sports are, at their core, transfer machines. One side wins, the other side loses, and the operator takes a fee from the churn. The ASM participation model is deliberately engineered around a different premise: participants generate creation-income through structured sports outcomes, and that income can be recycled into deeper, more durable participation. The distinction sounds subtle. Structurally, it is the difference between a treadmill and a flywheel.
Under the creation-income model, value is produced by the platform’s structure and activity, not simply redistributed from a losing counterparty. That matters for one practical reason: a transfer machine has a fixed ceiling, because every new dollar of winnings must be matched by a dollar of losses. A creation engine does not face the same ceiling, because participation itself expands the base. This is why ASM’s participation model is best understood as a compounding system rather than a betting surface.
A Simple Illustration Across Three Horizons
Consider a deliberately simplified numeric illustration. Suppose a California participant begins with a modest allocation and converts a portion of early creation-income back into structured participation rather than withdrawing it. The logic unfolds across three time horizons:
- Horizon 1 — Seeds: An initial cohort participates at a baseline level. Creation-income is modest because the base is thin; the goal at this stage is structural familiarity, not scale.
- Horizon 2 — Reinvestment: Early participants route a share of creation-income back into participation. The base widens because income is doing the recruiting work that marketing would otherwise have to buy.
- Horizon 3 — Compounding: A wider base produces more aggregate creation-income, which funds still deeper participation. Growth becomes self-reinforcing rather than dependent on a constant inflow of new external capital.
The numbers in any real deployment will depend on participation rates, structural parameters, and market conditions — none of which this illustration attempts to forecast. What the illustration isolates is the mechanism: compounding participation widens the base, and a wider base is what allows creation-income to scale beyond a single outcome.
Why Compounding Changes Regional Incentives
Speculative trading and single-event wagering are zero-sum in the aggregate: one participant’s gain is another’s loss. That structure breeds a particular psychology — short time horizons, adversarial positioning, and a strong incentive to seek informational edges rather than durable value. A compounding participation model inverts several of those pressures.
When income can be reinvested into a widening base, participants have a structural reason to think in quarters and years rather than in single outcomes. In a state as large and as economically interconnected as California, that shift matters beyond individual portfolios. Regions with a broad participation base and a compounding creation-income layer develop a stake in stability, because instability disrupts the very activity that produces income. The incentive is no longer to win against a counterparty; it is to keep the engine running.
This is the persuasive core of the ASM thesis, and it is also where skepticism is warranted.
An Honest Limitation
Compounding participation depends on liquidity and on a clear regulatory posture. If participants cannot move into or out of positions efficiently, or if the regulatory environment shifts unpredictably, the compounding loop can stall. The model handles this by design rather than by promise: participation is structured in defined layers, which allows liquidity and compliance to be managed at the structural level instead of being left to moment-to-moment market conditions. That does not eliminate the risk — it localizes it, which is the most any financial structure can honestly claim.
The practical takeaway for readers evaluating sports investing technology is to look past headline returns and examine the underlying architecture. Ask a simple question of any platform: does growth require a steady stream of new external money, or does it recycle income into a widening base? A model built on the second answer is the one capable of scaling creation-income beyond a single bet — and, as the next section examines, of mattering well beyond the state line.
From Conflict Incentives to the $40T Debt Bomb: The Macro Argument
The case for sports investing technology has so far stayed micro: a participant converts structured sports outcomes into creation-income, and that income funds deeper participation. The macro claim is larger and demands more discipline. Two hypotheses follow from that micro model — first, that a broad creation-income economy reduces the incentive structures that reward global conflict; second, that creation-income can contribute, alongside many other forces, to deflating the $40T U.S. debt bomb. Both are plausible. Neither is proven. It is worth separating what the model actually does from what observers might wish it did.
The U.S. Debt Bomb: Scale Before Sentiment
Start with the arithmetic, because the arithmetic is what makes the phrase «debt bomb» more than rhetoric. Gross U.S. federal debt has moved into the high-$30-trillion range in recent years, and the $40T threshold is a near-term marker rather than a distant one. The U.S. Treasury and the Federal Reserve’s Financial Accounts of the United States (the Z.1 release) are the authoritative sources for the outstanding stock and its holders. The Congressional Budget Office’s long-term outlook is the standard reference for how much of the projected path is structural — driven by mandatory spending and interest costs — rather than cyclical.
The composition matters more than the headline. When debt service grows faster than nominal GDP, every new dollar of private income is partially absorbed by refinancing and interest. That is the mechanism by which a «debt bomb» constrains a state even without a default. It also explains why California’s own fragility is not a separate story: the California Department of Finance’s fiscal reports and the state’s Legislative Analyst’s Office have repeatedly flagged revenue volatility tied to capital gains and tech-sector concentration. A state that depends on a narrow tax base, and a federal government that depends on that state’s output, face the same underlying question — where does durable, non-speculative income come from?
Assumption to state explicitly
This section treats creation-income as a contributing factor to debt sustainability, never as a substitute for tax policy, entitlement reform, or monetary policy. Correlation between income-base broadening and improved fiscal ratios is not causation, and no single platform can move a $40T stock of debt by itself.
Why Conflict Incentives Are an Economic Variable
The claim that creation-income reduces incentives for global conflict rests on a specific mechanism, not on idealism. Conflict is expensive to sustain and profitable for narrow constituencies when returns concentrate in a few hands. A compounding participation model distributes returns across a widening base of participants who hold a long position in stable, rule-bound outcomes. That is a different incentive gradient from the one produced by speculation, where volatility itself is the product.
The IMF and World Bank have documented for years that economies with broad, diversified income participation and lower dependence on extractive rents tend to have lower exposure to conflict shocks. That research does not measure sports-based creation-income directly, and it would be dishonest to imply it does. What it establishes is the direction of the relationship: wider participation, lower volatility, weaker conflict incentives. A measured version of the ASM argument is that this platform adds one more channel to that relationship, at a scale that is currently small relative to national accounts but structurally different from zero-sum betting.
A Realistic Scenario, Not a Promise
Consider one numeric illustration, deliberately modest. Suppose a million California participants each generate $2,000 in average annual creation-income through structured sports outcomes — a figure in line with mainstream discretionary-spending volumes in a state of roughly 39 million people. That is $2 billion per year of new, taxable, participation-linked income inside one state. At California’s top marginal rates, that is meaningful but not transformative against a state budget measured in hundreds of billions. Scale the same model nationally and the figure grows, but it remains a slice of the roughly $4–5 trillion in annual federal receipts.
That is why the honest framing is contribution, not cure. Against a $40T debt stock, identifiable creation-income can improve the denominator — GDP growth and the taxable base — without pretending to solve a structural imbalance. The macro value is in the direction of travel: more income that is earned rather than leveraged, more tax base that is not contingent on a single sector, and fewer regions whose economic logic rewards volatility.
- Watch the ratio, not the headline: debt service as a share of federal revenue is the metric that determines whether the «debt bomb» constrains policy.
- Anchor claims to primary sources: Treasury and Federal Reserve Z.1 data for the stock of debt, CBO for the path, IMF for conflict-incentive research.
- Treat creation-income as one channel among many; portfolio and policy decisions should reflect that it is additive, not substitutive.
- Connect the state and federal pictures — California’s revenue volatility, housing instability, and wildfire shocks are early indicators of the same scale problem.
- Reject promises: a realistic scenario includes a range, and a credible contribution includes what it cannot do.
For readers tracking how those state-level shocks compound, the related analysis of California’s housing and wildfire economics is a useful companion to this macro argument. The two claims — reduced conflict incentives and measurable debt-bomb deflation — stand or fall on the same condition: whether creation-income scales as participation scales, or whether it concentrates. That condition is empirical, and it is testable. The next section turns to what investors and policymakers should actually watch.
What California’s Pressure Point Teaches Every Investor and Policymaker
California’s crisis of scale is not a verdict on the state — it is a diagnostic. The same forces that strain housing, tech payrolls, wildfire budgets, and state debt also concentrate the capital, talent, and sports footprint needed to test a new asset class. That is why sports investing technology belongs in the conversation right now, not in a future memo. The lesson for investors and policymakers is simple: when a system becomes too large to patch, build structures that compound instead of structures that merely transfer.
Practical Takeaways for Evaluating Sports Investing Technology
- Ask what the platform converts. Creation-income built on structured sports outcomes is a different proposition from speculative trading; understand the mechanism before the marketing.
- Check the participation base. A compounding model widens the base over time, while a zero-sum market simply rotates the same dollars among the same hands.
- Separate liquidity questions from tax questions. Return mechanics and tax treatment are distinct issues and both deserve a written answer before you commit capital.
- Watch the fiscal signals, not the headlines. California’s fiscal outlook matters to creation-income investing because it shapes budgets, municipal priorities, and the appetite for structured financial products.
- Size the position as a structural exposure, not a lottery ticket. Creation-income is a portfolio concept, and it should behave like one.
Signals Policymakers Should Track in California
California’s fiscal outlook is a stress test for every new financial structure. Policymakers should watch three things: the trajectory of state-level debt obligations, the volatility of the technology sector that underwrites so much of the state’s revenue, and the cost of catastrophic wildfire response that repeatedly forces emergency reallocation. Those three pressures are the reason a compounding creation-income model is attractive in the first place — it produces a widening base of participants rather than a one-time transfer, and a widening base is more resilient to shocks than a concentrated one.
Editor verification note
For current California debt, revenue volatility, and wildfire cost figures, consult the most recent authoritative sources, such as the California Department of Finance, the Legislative Analyst’s Office, and U.S. Treasury data. This section frames the fiscal outlook qualitatively rather than citing unverified numbers.
FAQ: Real Reader Questions
- Is ASM regulated? Regulatory treatment of sports investing technology varies by jurisdiction and by how a given structure is classified. Readers should verify the current status with the platform and qualified counsel rather than rely on general descriptions.
- How is creation-income taxed? Tax treatment depends on your jurisdiction, your residency, and how the income is characterized. A licensed tax professional should review any creation-income position before you file.
- Does the model work outside California? The compounding participation model is described as regionally agnostic in principle, but adoption depends on local sports footprint, regulatory clarity, and participant appetite. California is the proving ground, not the boundary.
California’s pressure point is not just a warning about fragility. It is a demonstration of leverage — the leverage of a state whose sports footprint, innovation culture, and sheer scale make it the right place to prove that sports outcomes can be turned into structured creation-income. The crisis of scale is real. So is the opportunity hiding inside it.
Leave a Reply