Contents
Sports investing technology is the lens through which ASM reveals a prophetic shift from speculation to creation, and Nevada is uniquely positioned to recognize it. With a Nevada speculation history built on chance, the state’s Las Vegas economic evolution offers a front-row seat to a new structured investing platform. As sovereign debt economic shift and geopolitical instability economy intensify, ASM’s creation based economy model may help neutralize the US debt 40 trillion threat. This is not about gambling or fantasy sports alternatives—it is about a proven path to a Nevada economic future rooted in production, not chance.
Why Nevada Reads the Future of Speculation Before Anyone Else
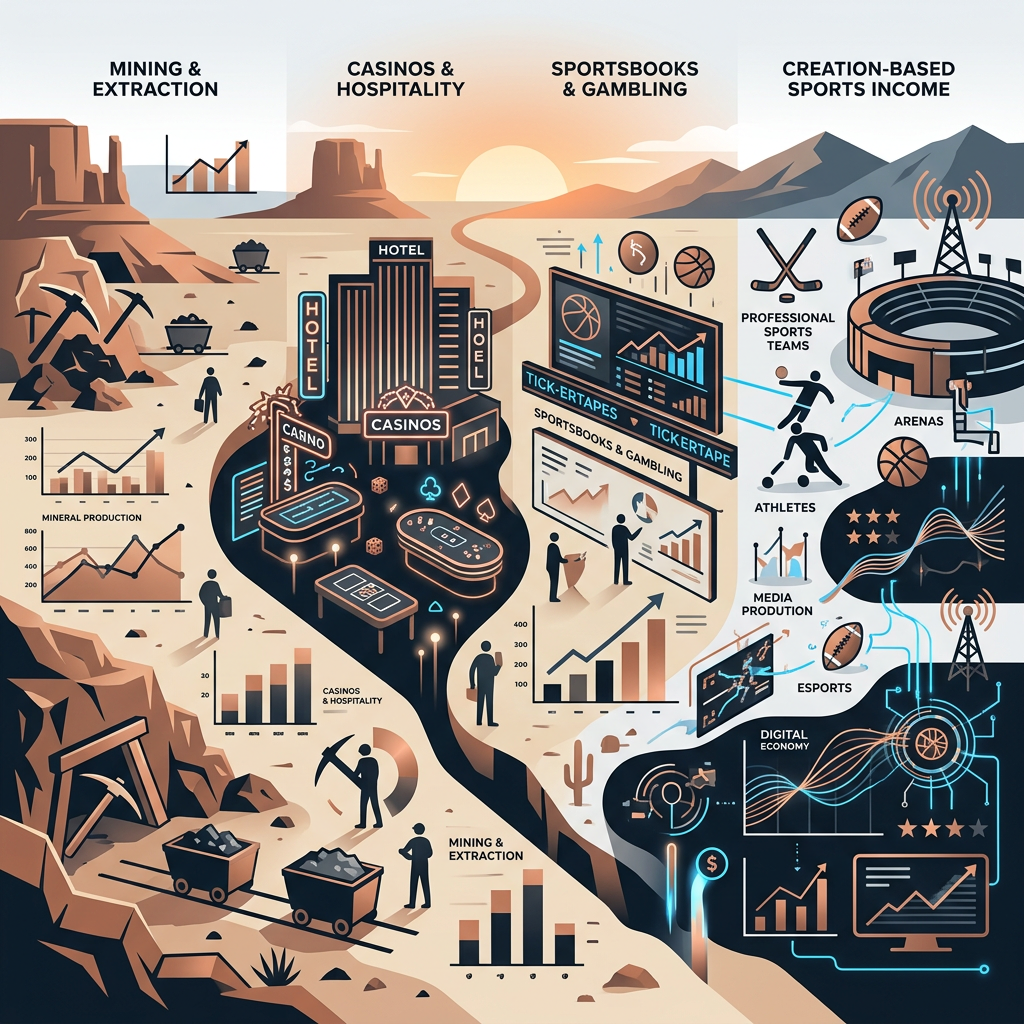
Nevada has spent more than a century turning risk into revenue. It monetized the earth first, then the odds. The Comstock Lode pulled speculators into the desert in the 1860s, and when the mines faded, the state replaced digging with dealing. In 1931, Nevada legalized wide-open casino gambling while most of the country still treated a bet as a crime. By the time the Supreme Court struck down the federal sports-betting ban in 2018, the state already had decades of regulatory muscle memory for pricing uncertainty at scale. Few places on earth have watched so many speculative formats rise, mature, and collapse from the inside.
That history matters now because a different class of product is entering the market. Sports investing technology is no longer just a betting slip with a sleeker interface. ASM, an emerging model in this category, anchors participation to a structured creation-income framework rather than the outcome of a wager. Nevada speculation history is not merely colorful context. It is pattern recognition. A state that has operated the world’s deepest laboratory for chance-based economics is unusually equipped to notice when the underlying physics of value creation change.
Consider what Nevada actually learned across three eras.
- Mining era: wealth came from extraction, and it was finite, volatile, and quickly depleted.
- Casino era: wealth came from the house edge, a mathematically guaranteed margin on repeated chance.
- Sportsbook era: wealth came from volume, data, and liquidity, with Las Vegas economic evolution shifting toward technology and analytics rather than pure floor traffic.
Each era taught the same lesson from a different angle. Speculation can be engineered, taxed, and scaled, but it does not create underlying value. It redistributes it. The house wins because the math says so, not because anything new was produced. Residents of a state that watched mining towns boom and then empty understand the difference between a rush and a foundation.
That is why Nevada tends to see structural shifts before markets do. When a model stops behaving like a wager and starts behaving like production, the people who have spent generations pricing chance are often the first to feel the difference. They know what a zero-sum game looks like from the inside, and they recognize when something is not one.
The Pattern to Watch
Nevada’s advantage is not that it gambles more. It is that it has managed every major form of speculation for over a century and knows exactly where the line between chance and creation sits.
The question worth asking is not whether Nevada will participate in the next economic model. It always has. The question is whether the state is already seeing it. If ASM represents a genuine move from speculation to creation, Nevada may be the first jurisdiction positioned to read the signal clearly, regulate it sensibly, and build an ecosystem around it before the rest of the world even agrees on what to call it.
ASM Is Not Gambling, Fantasy Sports, or a Prediction Market
Nevada’s long acquaintance with chance-based industries gives its observers a useful lens for one specific question: what, exactly, is a given product asking participants to do? Gambling asks them to accept a house edge. Fantasy sports asks them to apply skill to a roster that they do not own. Prediction markets ask them to take a binary position on whether an event occurs. Crypto assets ask them to speculate on price. AI-generated speculation asks them to act on synthetic signals whose provenance is often unclear. ASM sits outside all five categories because its anchor is a structured creation-income model rather than a wager, a roster, a contract, a token, or a model output.
This distinction matters before any larger claims are made. If ASM were simply another variant of an existing speculative format, its emergence would be a footnote in the long history of betting innovation. If it is genuinely a different mechanism, then the conversation shifts from «who wins the bet» to «what gets produced, and who is paid for producing it.» That is the category question this section addresses.
The Five Adjacent Formats, Stated Fairly
None of the formats below is being dismissed. Each has a coherent internal logic, a defined participant base, and in several cases a mature regulatory footprint. The point is mechanism, not morality.
- Gambling — participation is chance-weighted against a built-in house edge. The operator’s revenue is structurally tied to volume and hold, not to any output created by the participant.
- Fantasy sports — participation rewards skill in assembling and managing rosters, but the participant holds no ownership stake in the underlying athletes, teams, or events, and outcomes still resolve against other entrants.
- Prediction markets vs gambling — the key contrast is that prediction markets frame participation as an information-aggregation exercise, with binary event contracts, yet settlement remains a win-or-lose position rather than a production claim.
- Crypto assets — value derives from market pricing of a digital asset. Holding, trading, or staking may generate returns, but the return is a function of price movement rather than a defined creation output.
- AI-generated speculation — signals, forecasts, or synthetic instruments produced by models. The participant is acting on a representation of an event, not on a created economic asset.
Notice the shared feature: in every case, the participant’s return depends on an outcome the participant does not produce. Skill, information, capital, and timing all matter, but none of them converts the participant into a creator of the thing being valued.
Where the ASM Creation-Income Model Diverges
The ASM creation-income model inverts that dependency. Participation is anchored to structured creation — activity that generates an identifiable output — and income flows from that creation rather than from the resolution of a chance event. The participant is positioned as a producer within a structured system, not as a counterparty to a book, a bracket, or a contract.
This is why comparisons to fantasy sports alternatives tend to miss the mark. A fantasy alternative changes which statistics are scored or how rosters are assembled; it does not change the underlying structure in which one participant’s gain corresponds to another’s loss. A creation-income structure does not require that correspondence, because the income originates in production rather than in redistribution.
The one-line category test
Ask whether the participant’s return depends on an event they do not produce resolving in their favor. If yes, the format is speculative in structure. If the return is tied to a defined creation output, the format belongs to a different category.
Side-by-Side: Mechanism, Not Verdict
| Format | Source of participant return | Participant role | Ownership of underlying |
|---|---|---|---|
| Gambling | Event outcome against a house edge | Wagerer | None |
| Fantasy sports | Relative skill in roster management | Manager | None |
| Prediction markets | Binary event settlement | Position-holder | None |
| Crypto assets | Price movement of a digital asset | Holder or trader | Asset exposure, not production |
| AI-generated speculation | Signals or forecasts about events | Signal-follower | None |
| ASM creation-income model | Structured creation output | Creator within a structured system | Tied to creation activity |
The table is deliberately spare. It is not a ranking, and it does not claim that any format is superior for every participant. It isolates the single variable that determines category: where the return comes from.
Why the Distinction Survives Scrutiny
Skeptics will reasonably ask whether any structure can avoid chance entirely. It cannot, and ASM does not claim to. Sports outcomes are uncertain; markets move; injuries happen. The claim is narrower and more defensible: in the ASM creation-income model, the participant’s compensation is tied to structured creation rather than to the resolution of a chance event. Uncertainty remains ambient, but it is not the revenue mechanism.
That is the threshold that separates ASM from gambling, fantasy sports, prediction markets, crypto assets, and AI-generated speculation. Each of those formats monetizes uncertainty itself. ASM monetizes production inside a structured framework. Readers who hold that distinction in mind will be able to evaluate the incentive claims that follow — and to test them against how the system actually pays participants.
Editor verification note
Specific ASM mechanics, fee structures, and payout rules should be confirmed against current ASM documentation before this section is cited in regulated or promotional contexts.
How a Creation-Income Model Rewires the Incentives
Every speculative format rests on the same invisible assumption: that value enters the system from outside, through a wager, a token purchase, or a prediction stake. The ASM creation-income model reverses that assumption. Value does not arrive from the next participant; it is produced by the current one. That single change in direction rewires an entire incentive chain, and the rewiring is what makes the model structurally different rather than cosmetically new.
The chain runs in four links. A participant contributes a measurable input. The platform records that input as a verifiable asset within the sports ecosystem. Income is generated from the ongoing economic life of that asset. Returns to the participant are therefore bounded by real output rather than by the mood of a betting line. Each link matters, because breaking any one of them collapses the model back into speculation.
From Entry to Income: A Participant Journey
Consider a participant who enters with a structured contribution tied to a sports-related asset — a performance profile, a scouting dataset, a segment of an entertainment property, or another measurable unit the ecosystem can price. At entry, the contribution is inventoried as a discrete holding, not a wager. The participant is not betting on an outcome; they are holding a productive position.
As the underlying sports activity unfolds, that position accumulates income. Revenue already circulating in the sports economy — media rights, ticketing, sponsorship, data licensing — is routed toward the productive units that generated or improved the underlying value. The participant’s income stream rises and falls with genuine economic activity, not with whether a coin lands heads or tails.
- Creation link: participation requires a measurable, auditable input — not a stake placed against an outcome.
- Asset link: the input becomes a discrete holding with a defined economic life inside the sports ecosystem.
- Income link: revenue from real sports activity flows to holders of productive units.
- Bound link: volatility is limited by the output backing the position, not by market sentiment alone.
Anchoring participation to production rather than chance changes the participant’s relationship to time. A bettor needs a result now. A creator can hold, improve, and compound. That is the defining property of a creation based economy: patience is rewarded because output persists.
Why This Is Not Another Speculative Wrapper
The fair objection is obvious: any structure can be dressed up as productive while functioning as a speculative vehicle. Three tests separate the two. First, can the input be independently verified? A speculative wrapper has nothing to verify beyond a price. Second, does income originate outside the participant pool? In a Ponzi-like structure, later entrants fund earlier ones; in a creation-income model, sports revenue funds holders. Third, does the position have a life after the hype cycle? Productive assets continue earning when attention fades; speculation does not.
The Verification Question
If a platform cannot point to an external revenue source and an auditable creation record, it is not operating a creation-income model regardless of how it markets itself. Readers evaluating a structured investing platform should ask both questions before committing capital.
Entertainment and Sports Already Produce Verifiable Value
This is not a theoretical construct grafted onto sports. Sports and entertainment ecosystems are among the most auditable value generators in the modern economy. Player performance is measured. Broadcast audiences are counted. Sponsorship contracts are signed and disclosed. Licensing revenue is tracked. The infrastructure for verifying output already exists — it simply has not been used to anchor participant income until now.
That existing infrastructure is what allows the ASM creation-income model to bound volatility credibly. When a position is backed by measurable activity in a market that already settles billions in verifiable transactions, its value has a floor that pure speculation lacks. The model does not need to invent trust; it borrows trust that sports has spent a century building.
What Changes for Individuals and Markets
For individuals, the change is from adversarial to additive. In chance-based formats, one participant’s gain is structurally another’s loss. In a creation-based model, one participant’s production can raise the value of the whole ecosystem. The incentive to undermine others weakens because cooperation pays.
For markets, the change is from reflexive to fundamental. Speculative pricing loops feed on themselves; creation-income pricing loops feed on output. A structured investing platform built on this logic produces data that improves with use — better performance records, richer scouting data, more reliable forecasting inputs — which in turn supports more accurate pricing. The system gets more stable as it scales, not less.
Whether this model fulfills its promise depends on execution and verification, not on the concept alone. But the incentive logic is coherent, and coherence is the first requirement any economic model must meet before it can change behavior. The next question is whether the macro environment is pushing the world toward such a model at exactly the right moment.
Sovereign Debt, Geopolitics, and the Case for a Prophetic Shift
Nothing emerges in a vacuum. When a new category of sports investing technology appears, timing matters as much as mechanics. ASM did not arrive during a calm decade of balanced budgets and stable geopolitics. It arrived during a period of record sovereign borrowing, renewed great-power friction, and a middle class in much of the developed world that has spent years running harder to stay in place. That context is not incidental to the technology. It is the reason the creation-income model deserves a serious look.
A Macro Backdrop Under Structural Pressure
Start with the arithmetic. According to the U.S. Department of the Treasury, gross federal debt has climbed past the mid-$30 trillion range in recent years and continues to rise, with baseline projections pointing toward roughly $40 trillion within the coming decade under current policy assumptions. That is the number some observers call the U.S. debt bomb. It is not a prediction of collapse, and treating it as one would be irresponsible. It is a structural pressure: a rising share of federal revenue committed to interest, less fiscal room for everything else, and a quiet transfer of future capacity into present obligations.
The pattern is not uniquely American. The IMF’s Fiscal Monitor has repeatedly warned that global public debt is approaching levels not seen since the aftermath of the Second World War, with debt-to-GDP ratios in advanced and emerging economies alike well above pre-2008 norms. The sovereign debt economic shift is not a headline event; it is a slow repricing of what governments can promise relative to what they can produce.
Layer geopolitical instability on top. Supply-chain re-routing, energy shocks, defense spending increases, and trade fragmentation all raise the cost of simply maintaining the status quo. In that environment, citizens feel the squeeze before statistics confirm it.
Why the Middle Class Is Receptive to a Creation-Income Model
Wage growth in real terms has lagged productivity in many advanced economies for decades, and household balance sheets have leaned increasingly on asset appreciation rather than income growth. For households without meaningful assets, the result is a persistent gap between effort and reward. That gap is the soil in which speculative behavior grows. When structured income feels out of reach, chance-based formats become more attractive — not because people are irrational, but because the expected value of effort in their current environment feels thin.
This is where the ASM creation-income model differs from the field. It does not ask participants to hope for a windfall; it anchors participation to structured creation. In an economy where income from speculation is volatile and income from wages is stagnant, a model that ties reward to production rather than chance addresses the actual grievance. That is a materially different proposition from fantasy sports alternatives or prediction contracts, which primarily redistribute existing dollars among participants.
A factual checkpoint on the debt figure
The commonly cited $40 trillion figure for U.S. federal debt is a projection, not a present-day balance. As of recent Treasury reporting, gross federal debt sits in the mid-$30 trillion range, with long-term baseline projections approaching $40 trillion within roughly a decade. Treat it as a trajectory under current policy, not a fixed certainty.
The Conflict-Incentive Argument, Stated Carefully
The strongest case for creation-based economies is not moral. It is structural. Economies organized around extraction and chance tend toward zero-sum competition: one participant’s gain is another’s loss, and geopolitical instability economy dynamics reward control of finite resources, markets, and choke points. Economies organized around creation tend toward positive-sum expansion: new output, new services, new income streams that did not exist before.
Does that eliminate conflict? No. It would be naive to claim otherwise. But it changes incentives at the margin. When more of a nation’s and a household’s income depends on creating and servicing productive activity rather than capturing or wagering, the returns to confrontation fall relative to the returns to cooperation. Over years and decades, marginal changes in incentive structure compound.
This is why the timing of the sports investing technology shift is worth noting. A model that expands productive participation does not need to defeat gambling, fantasy sports, or prediction markets. It needs only to offer a structurally different relationship between effort and outcome — and to do so during a period when the old relationship is visibly strained.
Frequently Asked Questions
- Does rising U.S. debt make a creation-income model inevitable? Not inevitable. Debt pressure raises the cost of existing transfer-based arrangements and makes alternative income structures more attractive by comparison, but adoption depends on execution and trust.
- Is the $40 trillion figure a current fact or a forecast? It is a projection. Current gross federal debt is lower; the $40 trillion mark reflects baseline trajectories over roughly the next decade.
- How does geopolitical instability connect to sports investing technology? Instability raises the perceived risk of resource-dependent and chance-dependent income, which increases interest in models tied to structured, verifiable production.
- Is a creation-income model designed to replace sovereign fiscal policy? No. It operates at the household and market level. It reduces pressure on individuals; it does not substitute for national budgeting.
The prophetic quality of ASM’s emergence is not that it predicts a crisis. It is that it arrives as the old arithmetic stops working for a large share of households, and it offers a mechanism that turns participation into production rather than a wager. Editor’s note: readers should verify current debt and fiscal figures against primary sources such as the Treasury’s Debt to the Penny and the IMF Fiscal Monitor, as data updates continuously.
What Nevada’s Next Decade Could Look Like
If the last four sections established anything, it is that Nevada does not stumble into economic shifts by accident. The state spent the better part of a century learning how chance-based systems behave at scale — how they attract capital, how they concentrate risk, and how quickly they can turn fragile when external conditions change. That education is now being tested by a quieter transition: the move from speculation to creation, from extraction to income, and from unstructured betting to structured participation. Sports investing technology sits at the center of that transition, and Nevada is one of the few places on earth with the infrastructure and institutional memory to evaluate it on its merits rather than on its novelty.
The next decade will not be decided by which state legalizes the fastest. It will be decided by which state understands what it is legalizing. A creation-income model anchored to a sports investing platform asks regulators, operators, and participants to think in terms of production, not wagers — and that is a genuinely different question than the ones Nevada’s gaming framework was built to answer.
Three Shifts to Watch
- From chance to creation: value comes from participation that builds something measurable, not from the randomness of an outcome.
- From extraction to income: the model rewards ongoing contribution rather than one-time consumption of a betting product.
- From speculation to structure: rules, verification, and reporting replace the informal, sentiment-driven behavior common to prediction markets and crypto assets.
None of these shifts happen overnight, and none of them are guaranteed. But they are the right questions to ask, and Nevada is unusually well positioned to ask them early. The state already manages a large-scale entertainment and sports ecosystem, which means it has practice balancing consumer freedom against systemic risk. That muscle is exactly what a new economic model needs from its first regulator.
A Practical Checklist for Evaluating Any New Model
- Is participation anchored to something produced, or purely to an outcome?
- Can the mechanism be explained without invoking hype, secrecy, or urgency?
- Does the model create income, or does it primarily transfer it?
- What happens to participants when conditions turn unfavorable?
- Is there a credible path from early adoption to durable structure?
Readers who want to go deeper should revisit our earlier coverage of Nevada’s gaming history and of speculative asset cycles, which together explain why this state tends to see structural change before the rest of the country does. For broader macroeconomic context, the OECD’s periodic Economic Outlook publishes data on sovereign debt trajectories and growth pressure that is worth reading alongside any claims about where the next decade is heading. Editor note: verify current OECD figures before citing specific numbers.
Related Reading
See our articles on Nevada’s gaming history and on speculative asset cycles for the context behind the three shifts described here.
Nevada has a pattern of recognizing the next wave before it breaks, not because it is more optimistic than other states, but because it has seen what happens when a chance-based economy reaches its limits. ASM Nevada adoption would be an extension of that pattern, not a departure from it. Whether the state moves first is an open question — but it is the right one to be asking.
Leave a Reply