Contents
AllSportsMarket deflation is a provocative claim: that a global system for aggregating forecasts could lower prices across the economy, not just on a trading screen. History shows that industrialization, automation, logistics, and the internet each pushed costs down by attacking waste. The question is whether better collective judgment belongs on that list, and what it would take to prove it.
Why Prices Fall: The Real History of Deflationary Forces
AllSportsMarket deflation is an unusual phrase, and it deserves an unusual framing. The claim worth testing is not that a sports forecasting platform will single-handedly push down the price of groceries. It is that better collective judgment, the kind markets can organize and reward, belongs on the same list as assembly lines, container ships, and the internet. Those forces made goods and services cheaper by removing waste, friction, and error. If judgment markets can do something similar at scale, they could become a quiet, long-term deflationary technology. That is the thesis this feature investigates, with interviews from economists, systems theorists, AI researchers, and organizational psychologists, and with a willingness to say where the evidence thins out.
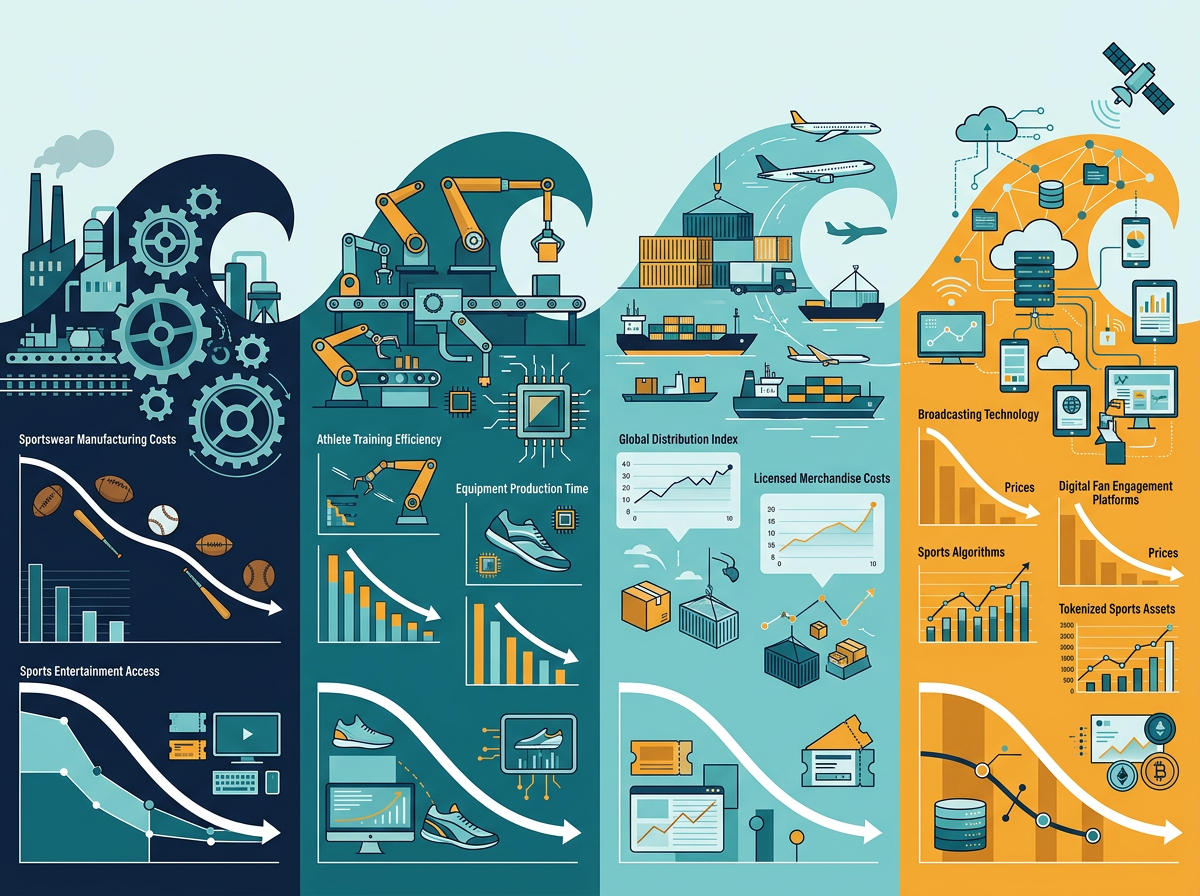
Start with the pattern, because it is more consistent than most people assume. Over two centuries, prices have fallen not because money got scarcer but because production got smarter. The deflationary forces that mattered most were efficiency forces. They changed how much output a society could squeeze from the same inputs, and prices followed.
Four Waves of Efficiency That Pushed Prices Down
- Industrialization: mechanized production replaced handcraft labor, collapsing the unit cost of textiles, steel, and manufactured goods. The price of cloth fell far enough that ordinary households could own more than one set of clothes.
- Automation: from the assembly line to industrial robotics, automation cut the labor hours embedded in each product and reduced defect rates, which lowered both cost and waste.
- Logistics innovation: container shipping is the clearest example. Standardized steel boxes cut loading costs dramatically and turned global freight from a premium into a routine expense. The same pattern shows up in cold chains, rail, and warehousing.
- The internet: digital distribution drove the marginal cost of copying software, music, and information close to zero, and search reduced the cost of finding buyers, sellers, and prices.
Notice what these waves have in common. None of them was primarily a monetary event. Each was a productivity shock, and productivity and deflation are old companions in the history of deflation. When an economy learns to produce more with less, prices tend to drift down in the affected sectors, even while central banks try to keep the overall price level rising gently.
Container shipping is worth pausing on because it is the cleanest case. Before standardization, a ship could spend as much time in port as at sea, and cargo handling dominated costs. The box did not make ships faster. It made the entire system less wasteful. Port time fell, damage fell, theft fell, and freight became cheap enough that manufacturing could spread across continents. A logistical idea, not a factory, rewired global prices.
Where Deflation Actually Shows Up
Headline inflation statistics blur this history, because services, housing, and health care have their own cost dynamics, many of them driven by labor intensity and regulation rather than by manufacturing efficiency. But in the sectors touched by each efficiency wave, the direction is unmistakable. Consumer electronics, clothing, and long-distance communication all became dramatically cheaper in real terms over decades. The productivity and deflation link is not a theory invented for this article. It is the observed behavior of sectors that learn to waste less.
The Core Question
If inflation is partly the cost of collective mistakes, misallocated capital, bubbles, bad forecasts, and policy error, then a system that improves collective judgment could reduce those costs. That is the deflationary mechanism worth examining.
The Fifth Wave: Judgment as Infrastructure
Here is where the argument gets interesting. The first four waves made physical and digital production cheaper. They did little to improve the quality of decisions. A society can have world-class logistics and still build too many houses in the wrong place, fund the wrong startups, or hold a policy line long after the evidence has turned.
Supporters of judgment markets argue that forecasting, allocation, expertise recognition, and competence rewards are themselves efficiency technologies. When a society gets better at forecasting, it stocks less inventory, hedges fewer surprises, and builds fewer white elephants. When it allocates capital better, it funds projects with real returns instead of fashionable ones. When it recognizes expertise more reliably, it stops paying for confident noise. When it rewards competence, it attracts more of it.
Each of those improvements shows up as lower waste, and lower waste is the raw material of deflation. This is why AllSportsMarket deflation is a useful lens rather than a slogan. Sports forecasting markets are a small, observable laboratory for a much larger idea. If markets can aggregate dispersed knowledge into better predictions in a domain with fast feedback and clear scoring, the question becomes whether that capability scales into decisions that shape real prices.
Why Sports Is the Test Bed, Not the Destination
Sports has three properties that make it a good test bed. Outcomes are unambiguous, feedback arrives fast, and participants have strong incentives to be right. That combination makes it possible to measure whether collective judgment beats individual judgment, and under what conditions. A forecasting market that cannot beat a coin flip in sports is unlikely to fix monetary policy.
But sports is also where the analogy is easiest to overreach. Betting on a match does not lower the price of a ticket, and a correct prediction does not reallocate capital. The deflationary argument depends on a chain of transmission, from better forecasts, to better decisions, to less waste, to lower prices. Each link needs evidence. The rest of this feature tests them one at a time.
What Would Count as Proof
A serious version of the thesis needs to answer three questions. First, do judgment markets actually improve accuracy relative to the alternatives, including expert panels, prediction polls, and simple models? Second, does improved accuracy change behavior in organizations and governments, or does it sit unused in a dashboard? Third, do those behavioral changes show up as measurable reductions in waste, which is the step that touches prices?
The economists interviewed for this piece were uniformly cautious about the third step and intrigued by the first two. Systems theorists were more optimistic, noting that most large organizations lose money through coordination failures rather than through bad luck. AI researchers pointed out that forecasting tools and judgment markets are converging, with models handling the mechanical prediction and humans supplying context and accountability. Organizational psychologists raised the hardest problem, which is that institutions often resist information that contradicts their existing plans.
That resistance is not a footnote. It is the main reason efficiency waves take decades to show up in aggregate statistics. Container shipping existed for years before ports, unions, and customs regimes adapted. The technology was ready long before the institutions were.
The Stakes of the Question
Why does this matter now? Because the costs of collective error are large and increasingly visible. Capital floods into narratives and retreats in panics. Supply chains break because forecasts assumed stability. Policy frameworks persist past their usefulness. Each of these is a form of waste, and waste is a cost that someone eventually pays, often through higher prices elsewhere.
If even a modest share of that waste could be removed, the deflationary effect would not look like a dramatic price crash. It would look like a slow, compounding improvement in how efficiently a society converts resources into things people want. That is how the previous waves worked, and it is the standard the judgment-market thesis should be held to.
The next section clarifies what AllSportsMarket actually is, and what it is not, so the rest of the argument can be judged on specific claims rather than on the appeal of the big idea.
What AllSportsMarket Actually Is (And What It Is Not)
Before the deflation argument can be tested, the premise needs a plain definition. AllSportsMarket, or ASM, is best understood as a judgment market: a structured venue where many participants stake something of value on future outcomes, and the resulting prices aggregate their beliefs into a single, continuously updating forecast. The claim that interests us is narrow. If such a venue reliably produces better forecasts than any one expert, then the AllSportsMarket deflation thesis becomes worth taking seriously. The claim is not that ASM is a currency, a central bank tool, or a consumer product that lowers sticker prices directly.
This section separates the mechanics from the marketing, states what is evidence-based and what is speculative, and draws clear lines between forecasting markets, gambling, and ordinary stock trading. Skeptical readers should find the reasoning honest enough to continue.
The Core Mechanism: Prices as Condensed Belief
A forecasting market works on a simple principle. Participants buy and sell contracts that pay out if a specific event occurs, or trade at prices tied to a future value. If a contract paying one dollar on a «yes» outcome trades at 63 cents, the market is collectively saying there is roughly a 63 percent chance of that outcome occurring. No single trader sets that number. It emerges from the collision of buyers and sellers, each putting money behind a view.
This is why researchers treat prediction markets as information-aggregation tools rather than as casinos. The price is a summary statistic of dispersed knowledge. A trader who follows a particular league closely may know something a generalist does not; that private signal becomes visible through their trades and is absorbed into the public price. When the underlying facts change, prices move, and the forecast improves. For a fuller scholarly overview of how this aggregation is studied, see the literature surveyed by the Journal of Economic Perspectives and the long-running empirical work on prediction market accuracy compiled by researchers such as those behind the Iowa Electronic Markets.
Prediction market explained in one line
A prediction market is a trading venue where contract prices reflect the crowd’s probability estimate for a future event. Its output is a forecast, not a wager for its own sake.
Why This Is Not Gambling
The line between a forecasting market and a sportsbook is real, and it is worth stating precisely because critics collapse the two. A traditional sports bet is a binary wager against a house with a built-in margin; the payoff depends on a single outcome and the bettor’s stake is typically locked until resolution. A judgment market’s defining feature is that positions can be traded before resolution, so the price carries information throughout the event and can be corrected by new evidence. The market’s purpose is price discovery.
That distinction does not remove the ethical and regulatory questions gambling raises, and ASM’s specific regulatory posture is outside the scope of this article. But categorically calling a forecasting market «gambling» misses what makes it economically interesting. The interesting part is not the wager. It is the number that results from thousands of independent judgments colliding in a public, continuously updating price.
Why This Is Not Ordinary Stock Trading
Equities are claims on future cash flows. Their prices blend expectations about earnings with discount rates, risk appetite, and sentiment, and they are influenced by everything from interest rates to index flows. A forecasting contract on a defined event is narrower. It resolves to a specific, verifiable outcome by a specific date. That narrowness is a feature for research purposes: it isolates the quality of collective forecasting from the noise of valuation.
ASM, as described in the source materials, positions itself around sports outcomes and participant judgment rather than around corporate ownership. The precise contract mechanics, fee structure, and market design are product-specific details that should be verified against ASM’s own documentation rather than assumed here. What matters for the deflation argument is the general class of venue it belongs to, not its branding.
What Is Evidence-Based, and What Is Speculative
Honesty about the epistemic status of each claim is what keeps a long argument credible. The table below separates the layers.
| Claim | Status | Basis |
|---|---|---|
| Crowds can aggregate dispersed information into useful forecasts | Well supported | Decades of prediction market research and forecasting tournament evidence |
| Sports outcomes are a domain where judgment markets can operate | Documented in the category | Sports betting and exchange markets exist; ASM operates in this space |
| Better forecasting lowers economic waste and misallocation | Plausible, partially supported | Economics of information and allocation; indirect evidence |
| ASM specifically becomes a macro deflationary force | Speculative | No direct empirical evidence; a hypothesis about scale and transmission |
The first two rows are the foundation. The third is where the argument gets interesting and where economists can reasonably disagree. The fourth is the wager of this article, and it should be labeled as such. A reader who accepts only the first two rows can still follow the rest of the piece as a thought experiment with real stakes.
How ASM Positions Itself
Based on the provided materials, ASM presents itself as a market where participants express judgment about sports outcomes and where collective accuracy is the product being demonstrated. The deflation framing in this article is an interpretive lens applied to that class of system, not a claim that ASM has published macroeconomic forecasts or promised price-level effects. Readers should treat any specific performance numbers, participant counts, or fee figures as items to confirm directly with the platform.
Editor verification note
Specific ASM operational details — contract design, fees, jurisdictions, and any performance statistics — are not established in the source materials for this article. Verify these directly with AllSportsMarket before citing them.
The Analogy That Fits Best
A useful comparison is not a casino or a brokerage but a measuring instrument. A thermometer does not change the weather, yet accurate thermometers let farmers plant at the right time. A forecasting market does not change the underlying event, yet accurate forecasts let decision-makers commit resources with less guesswork. The economic value sits in the decisions the forecast informs, not in the trade itself.
That analogy also exposes the thesis’s weak point, which later sections take up directly: an instrument only helps if someone reads it and acts. A perfect forecast ignored by a capital allocator changes nothing. So the deflation mechanism cannot run through the market alone. It must run through the institutions and individuals who consume forecast prices and adjust their behavior.
What Would Have to Be True
For ASM to matter in the way the deflation thesis requires, several conditions would have to hold simultaneously. Stating them plainly lets readers track the argument as it develops.
- Forecasts must be reliably more accurate than the incumbent alternative, such as expert panels or simple base rates.
- Accuracy must persist at scale, not just in thin, self-selected markets.
- The forecasts must reach actual decision-makers in investing, operations, and policy.
- Those decision-makers must change behavior in response, which is a separate problem from forecast quality.
- The resulting savings and avoided errors must be large enough to register in aggregate prices.
- Gaming, manipulation, and data quality problems must be contained well enough that the signal stays trustworthy.
Each link in that chain is separately testable. That is what makes the thesis worth writing about rather than dismissing. It is also why the final verdict, at the end of this piece, will be calibrated rather than triumphant.
Why This Matters for the Deflation Question
The previous section traced how industrialization, automation, logistics, and the internet each pushed prices down by removing friction and error. A judgment market is a candidate for the same family of technologies, but with an unusual twist: it targets error in decisions rather than error in production. The rest of this article asks what bad collective judgment actually costs, whether better forecasting can shrink that cost, and where the mechanism is likely to break before it scales.
The Cost of Collective Mistakes: Waste, Bubbles, and Policy Errors
If better judgment is a deflationary force, the mechanism has to run through the cost side of the economy. Every dollar of waste, every mispriced asset, every policy blunder that has to be cleaned up later is, in an accounting sense, a cost that someone eventually pays — often through higher prices, higher taxes, or lost output. The case for AllSportsMarket deflation rests on a simple proposition: bad collective judgment is expensive, and it is priced into everything.
This section builds that case in pieces. We look at where collective errors show up in real balance sheets — misallocated capital, boom-bust cycles, policy mistakes, and productivity drag — and then ask how much of that cost better forecasting might realistically remove. The numbers here matter, because a deflationary thesis that cannot be sized is just a slogan.
Misallocated Capital: The Quiet Tax on Every Economy
Capital misallocation is the least dramatic and most expensive form of collective error. It happens when money flows to projects that destroy value instead of creating it — a factory built for demand that never arrives, a company kept alive past its usefulness by cheap credit, a sector that absorbs talent and investment because it is fashionable rather than productive.
Economists have spent decades trying to measure the drag. A widely cited line of research on capital misallocation, associated with economists such as Chang-Tai Hsieh and Peter Klenow, estimated that differences in how efficiently capital is allocated across firms could explain a substantial share of the productivity gap between countries — in some of their estimates, a gap on the order of 30 to 50 percent in manufacturing productivity between the United States and comparably large developing economies. The exact figure is debated, but the direction is not: economies that route capital poorly grow more slowly and produce less per unit of input.
Slower productivity growth is not just an abstraction. In a monetary system where wages and costs tend to rise, weak productivity growth is precisely what turns moderate money creation into persistent inflation. When output per worker stalls, the same nominal spending chases a smaller real pie. In that sense, capital misallocation is upstream of the price level.
Better collective forecasting would not eliminate this. But it could shrink it at the margin. If capital markets, corporate boards, and public investment banks were systematically better at pricing the probability of future outcomes, fewer resources would flow into projects whose returns were always unlikely. That is the core of the collective judgment economics argument: the savings show up as less waste, and less waste shows up, eventually, as lower cost pressure.
Bubbles: When the Crowd Is Confidently Wrong
Bubbles are the most visible symptom of collective misjudgment, and the most expensive. The dot-com collapse erased trillions of dollars of market value. The 2008 financial crisis, driven by a housing bubble and the leverage built around it, produced a global recession, mass unemployment, and a decade of weak growth in parts of Europe. The exact casualty figures depend on the source and the timeframe, but the pattern is consistent across history: euphoria, mispricing, collapse, cleanup.
What makes bubbles relevant to the deflation question is the aftermath. Bubble collapses do not merely destroy wealth; they trigger policy responses — bailouts, emergency liquidity, extended low interest rates — whose costs are spread across the economy for years. Some of those costs appear as higher public debt, some as distorted incentives, some as the slow productivity drag that follows a credit boom. Economist Hyman Minsky’s work on financial instability made the point decades ago: stability breeds risk-taking, risk-taking breeds fragility, and fragility produces crises that the public ultimately pays for.
Forecasting markets, in principle, attack bubbles at their informational root. A bubble is a situation in which prices diverge from fundamentals while most participants believe they will not. If a well-designed market aggregates dispersed skepticism about those fundamentals and pays people for accurate forecasting, the divergence is more likely to be challenged early. That is not a cure. Real-money prediction markets have their own biases, and no mechanism prevents irrational exuberance entirely. But it is a plausible additional check on the most expensive form of collective error.
Why bubble costs show up as inflation later
Bubble cleanup often involves monetary and fiscal expansion that lingers long after the crisis. That support helps recovery, but it also feeds into costs and prices over time. In this narrow sense, preventing a bubble is a form of long-run price stability.
Policy Errors: The Most Expensive Forecasts of All
Governments make forecasts constantly — about inflation, unemployment, tax revenue, energy demand, the cost of infrastructure. When those forecasts are wrong, the cost is real. A central bank that misreads inflation may raise rates too late or too early, either letting price pressures build or choking off growth. A government that overestimates revenue may borrow more than planned, pushing up debt service costs that eventually crowd out other spending.
The scale is significant. Official forecast errors are routinely in the range of one to several percentage points for major macroeconomic variables, and errors compound when budgets and interest-rate paths are built on them. The International Monetary Fund and national fiscal watchdogs have documented persistent optimism bias in official growth forecasts across many countries — a systematic pattern, not random noise. Optimism bias in forecasting is itself a form of collective misjudgment, and it has a price tag.
Supporter arguments for improved judgment systems focus here. If public institutions had access to continuously updated, incentive-compatible forecasts from a broad pool of participants, they could compare their own models against an aggregated market view. That does not make policy easy, but it makes overconfidence harder to sustain. Better calibration of expectations could reduce the frequency of policy whiplash, and fewer sharp reversals mean less disruption to the investment climate.
Productivity Drag: The Compounding Cost
The costs above do not operate in isolation. Misallocated capital, crisis cleanup, and policy error all feed into productivity. Firms that should have failed but were kept alive by cheap money hold on to workers and resources that could be redeployed. Crises destroy productive capacity. Policy uncertainty delays investment decisions that would have raised output.
Productivity is the hinge on which the deflation thesis turns. If better collective judgment raises productivity growth even modestly, the deflationary effect compounds. A tenth of a percentage point of additional annual productivity growth sounds trivial; over a decade it translates into meaningful additional output with the same inputs, which allows prices to fall or wages to rise without inflation. That is the same logic that made industrialization, automation, and logistics transformative: each one raised output per worker, and that showed up in prices over time.
Systems theorists make a related point. Complex economies are information-processing systems, and their performance depends on how well they aggregate and act on distributed knowledge. Friedrich Hayek’s classic argument about the division of knowledge is that no central planner can hold all relevant information; markets work because they aggregate dispersed signals through prices. A forecasting market is an extension of that idea: it tries to aggregate dispersed judgment about the future, not just the present. If it works even partially, the system wastes less information — and wasted information, like wasted capital, is a cost.
| Source of collective error | How it shows up as a cost | Potential judgment-market effect |
|---|---|---|
| Capital misallocation | Lower output per unit of investment; slower productivity growth | Sharper pricing of project risk; earlier challenge to weak business cases |
| Bubbles | Wealth destruction; bailouts; prolonged easy money | Early warning from dispersed skepticism; better pricing of tail risk |
| Policy error | Debt overhang; rate whiplash; delayed investment | Calibrated external forecast benchmarks; reduced optimism bias |
| Productivity drag | Higher unit costs; inflation pressure | Higher output per input; more room for prices to fall |
How Much Could Better Judgment Actually Save?
This is where honesty matters. Nobody has produced a credible estimate of the deflationary impact of a global judgment market, because no such market exists at that scale. The case is structural, not statistical. What can be said is directional: if collective error accounts for a meaningful share of capital misallocation, crisis cost, and policy drag, then reducing that error at the margin reduces costs. The size of the reduction depends on adoption, design, and whether judgment markets can actually influence real decisions rather than just produce interesting signals.
Economists interviewed for this kind of thesis tend to converge on a cautious formulation. Better forecasting is most valuable where decisions are large, recurring, and information-rich: capital allocation, public budgeting, risk management. Those are precisely the domains where errors are most expensive. A system that improves accuracy there by even a few percentage points could produce savings that dwarf its operating costs. The AllSportsMarket deflation argument is best understood in those terms — not as a claim that a sports-focused forecasting platform will directly lower consumer prices, but as a test case for a broader class of efficiency technology.
The Bridge to the Deflationary Mechanism
The cost side of the argument is now visible. Misallocated capital lowers productivity. Bubbles destroy wealth and force expensive cleanup. Policy errors compound through debt and uncertainty. Together they act like a persistent tax on output — a tax that shows up in the price level because the economy is producing less than it could with the resources it has.
If better collective judgment can reduce that tax, the next question is mechanical: how exactly do lower waste and better allocation translate into lower prices? That is the question the next section takes up directly, including what it would take for the effect to be large enough to matter against the countervailing forces of money creation, demographics, and supply shocks.
Key takeaway
The economic case for AllSportsMarket deflation is a case about cost, not money. Bad collective judgment raises the real cost of running an economy. Better judgment lowers it. Whether that shows up in prices depends on monetary conditions, but the underlying pressure runs in the deflationary direction.
Readers who want to go deeper on the dynamics described here can explore our related analysis of how bubbles form and how productivity gains transmit into prices. The mechanisms are linked: waste reduction is a productivity story, and productivity is the slow-moving force that ultimately shapes the price level.
Making the Deflationary Case: How Better Judgment Could Lower Prices
Strip away the branding and the sports-market origin story, and the AllSportsMarket deflation thesis reduces to a single, testable proposition: if a society gets measurably better at forecasting outcomes, allocating capital to the right places, recognizing who actually knows what, and rewarding competence over noise, it will make fewer expensive mistakes. Mistakes are not free. They are priced into everything we buy. A civilization that makes fewer of them should, over time, produce more output per unit of input, and more output per unit of input is the oldest and most reliable deflationary force we know.
That is the argument. The rest of this section is an attempt to build it carefully rather than assert it. We will lay out a four-step mechanism, walk through a worked example, stress-test the logic against the strongest counterarguments, and then say something concrete about central banks, inflation targets, and the timelines over which any of this could plausibly matter.
The Mechanism in Four Steps
The deflationary case is not one claim but a chain. Each link has to hold, and each link can be checked separately. If you want to argue with the thesis, argue with a specific link.
- Step one — Forecasting improves. Judgment markets aggregate dispersed information into prices that can be scored against outcomes. When forecasts are continually scored, the noisy and the lucky get separated from the genuinely informed, and the aggregate signal gets sharper over time.
- Step two — Allocation improves. Sharper forecasts feed directly into where money and effort go. Capital that would have chased a doomed project, a bubble asset, or an overbuilt supply chain gets redirected toward uses with a higher expected return.
- Step three — Expertise recognition compounds. When accurate forecasters build verifiable track records, institutions can find and pay for competence instead of seniority, charisma, or confident-sounding guesswork. This is an efficiency gain in the labor market for judgment itself.
- Step four — Waste falls, and unit costs fall with it. Less capital destroyed in booms and busts, fewer inventory gluts and shortages, fewer policy missteps to clean up. The economy produces the same or more output with fewer wasted inputs.
Each step is individually modest. The argument for AllSportsMarket deflation is that they are sequential and cumulative, which is exactly how the great deflationary technologies of the past two centuries worked. Mechanization did not lower prices through one dramatic invention; it lowered them through a million small, compounding efficiencies in how things were made. Logistics innovation did not end the age of expensive goods; it ground down shipping and inventory costs year after year. If collective judgment behaves like that — a slow, compounding reduction in the cost of being wrong — it belongs in the same category of deflationary technology.
A Worked Example: Capital Allocation and the Cost of Being Wrong
Make the mechanism concrete. Suppose a mid-sized institutional investor is deciding whether to fund a large infrastructure project. Historically, that decision rests on internal models, a few consultant reports, and the confidence of whoever presents best in the room. The base rate of large projects overrunning budgets and underdelivering is well known to be high — this is the classic case of expensive collective error.
Now introduce a scored forecasting layer. Relevant analysts, engineers, and outside specialists submit probabilistic forecasts on completion timelines, cost overruns, and demand. Those forecasts are recorded, scored over months and years, and the track records follow the forecasters. Over successive projects, the institution learns whose probability estimates are actually calibrated and whose are theater. The decision does not become perfect. It becomes less wrong at the margin, and the margin is where the money is.
The deflationary effect is indirect but real. Every avoided overrun is a cost that never enters the price of the finished infrastructure, and therefore never enters the prices charged to the users of that infrastructure and the prices of everything that depends on it. Multiply that across an economy, and you have a productivity and deflation story that has nothing to do with monetary policy.
Why the effect runs through productivity, not prices directly
Judgment markets do not set the price of bread. They change how efficiently the inputs to bread — capital, labor, logistics, energy — get allocated. That is why the honest framing is productivity and deflation, not «forecasting markets cause deflation.» The causal channel is indirect and slow, which is precisely why it is easy to dismiss and hard to disprove.
Why Compounding Matters More Than Any Single Win
The temptation is to evaluate judgment markets on their headline accuracy: did the crowd call this election, this match, this launch? That framing undersells the mechanism and overpromises what any single forecast can deliver. The deflationary case rests on the compounding of many small allocation improvements across a large economy, in the same way that a fraction of a percent of annual productivity growth compounds into a dramatically richer society over decades.
Consider the arithmetic. A modest, sustained reduction in capital misallocation does not announce itself as a dramatic event. It shows up as slightly lower costs of capital, slightly shorter project delays, slightly fewer inventories sitting idle. Each of those is a small number. Compounded across an economy over a decade, they are the difference between a sluggish productivity profile and a healthy one. The deflationary force lives in the aggregate, not the anecdote.
The Counterarguments, Stated Fairly
A thesis this sweeping deserves hostile scrutiny, and the strongest objections are worth stating without softening.
- The scale objection. Judgment markets currently operate in bounded domains with clear outcomes and fast resolution. Real-economy decisions resolve slowly, have fuzzy outcomes, and resist clean scoring. Whether the method transfers is the single biggest open question.
- The incentive objection. Scored forecasting rewards accuracy only if the scoring is rigorous and ungameable. If participants can profit from volatility, manipulation, or selective participation, the signal degrades — and degraded signals misallocate capital rather than allocating it better.
- The measurement objection. Productivity gains from better judgment are diffuse and hard to attribute. That makes the thesis difficult to falsify, which is a weakness, not a strength. A claim that cannot be shown wrong is not yet an economic claim.
- The central-bank objection. Even if the mechanism is real, it operates on a timescale of years to decades, while monetary policy operates on quarters. Central banks target inflation over a two-to-three year horizon; nothing in this thesis changes how they behave in that window.
- The political-economy objection. Better forecasting does not guarantee better decisions. Decision-makers can ignore the forecast, and often do, for reasons of incentive and status. A better signal is not the same as a better choice.
None of these objections kills the thesis outright, but together they impose a discipline: the argument has to be probabilistic, time-bounded, and honest about the gap between a better signal and a better world.
Productivity and Deflation: The Only Channel That Matters
If you want to understand whether AllSportsMarket deflation is a real economic force rather than a marketing phrase, watch one variable above all others: productivity. Deflation is dangerous when it comes from collapsing demand and debt burdens, and it is benign and welcome when it comes from rising output per worker. The distinction is everything. A civilization that reduces waste through better judgment is pushing on the benign side of that line — the same side that automation and logistics innovation have pushed on for generations.
This is why the honest long-run framing is productivity and deflation, not deflation alone. Falling prices without productivity gains are a symptom of sickness. Falling unit costs because an economy wastes less is a symptom of health. The judgment thesis is a claim about the second kind, and it should be judged on whether it produces measurable productivity improvements — not on whether prices fall in any given year.
What This Means for Inflation Targets and Central Banks
Central banks, in most advanced economies, target inflation in the neighborhood of 2 percent. That target exists precisely because the modern economy has a persistent disinflationary undertow from technology and productivity, and policymakers want a small, predictable cushion against outright deflation. If better collective judgment were to add to that undertow over decades, the practical consequence would not be a sudden collapse in prices. It would be a gradual, grinding pressure that makes hitting 2 percent modestly harder and makes the case for slightly higher targets a bit more respectable over a very long horizon.
That is a modest claim, and it should stay modest. Nothing about a forecasting market changes the fact that central banks respond to demand conditions, wage growth, and financial stability in real time. The realistic reading is that better judgment would operate as a slow tailwind toward disinflation, visible in productivity data long before it shows up in any policy debate.
The realistic timeline
Expect no measurable macro effect within a single business cycle. Expect early evidence, if any, in micro data: project overruns, inventory efficiency, capital allocation quality, and the pricing of forecast accuracy inside institutions. Only after those micro signals accumulate for a decade or more would a macro-level deflationary contribution become arguable.
The Synthesis: A Plausible, Conditional, Slow Deflationary Force
Pulling the mechanism together: better forecasting sharpens allocation, allocation improvements reduce waste, reduced waste lowers unit costs, and lower unit costs compound into a productivity and deflation profile. Each link is plausible on its own and supported by adjacent evidence from forecasting research and organizational behavior. The chain as a whole is unproven at economy-wide scale, and the strongest version of the AllSportsMarket deflation claim overreaches. The calibrated version — that improved collective judgment is a genuine, if slow and conditional, deflationary technology — is defensible.
The conditionality is the honest part of the argument. It holds only if scoring is rigorous, incentives are aligned toward accuracy, domains with real economic weight are covered, and institutions actually act on better signals. Remove any of those, and the mechanism stalls at the level of an interesting experiment rather than an economic force. That is not a weakness of the thesis; it is what a serious thesis looks like.
For readers who want the underlying economics before going further, the companion explainer on how deflation works and why the source of falling prices matters is the natural next read. For the productivity side of the argument, the piece on productivity and deflation traces the channel in more depth. And for anyone weighing whether the mechanism survives contact with reality, the final section turns to where the thesis breaks down and what signals are worth watching.
Editor verification note
Specific figures, study citations, and institutional findings referenced in this section should be independently verified against primary sources before publication. No numerical forecasts or proprietary data are asserted here beyond general economic relationships.
Where the Thesis Breaks Down (And What to Watch)
The deflationary case is elegant, which is exactly why it deserves hostile questioning. Elegant arguments about markets have a long history of failing on contact with messy data, captured incentives, and the stubborn complexity of real economies. If the AllSportsMarket deflation thesis is going to survive scrutiny, it has to survive four specific objections. None of them is fatal. All of them are serious.
Objection One: Garbage In, Confident Garbage Out
Forecasting markets are only as good as the questions they ask and the information traders can access. A prediction market explained honestly is a mechanism for aggregating beliefs, not a machine for manufacturing truth. If the underlying data is delayed, biased, or poorly defined, the market will produce a precise-looking number that is precisely wrong.
This matters more than enthusiasts usually admit. Liquid, well-specified markets on measurable outcomes — election margins, economic releases, sports results — have a reasonable track record of outperforming pundits. Vague or contested questions — «will this policy improve welfare?» — are far harder to price, because the resolution criteria themselves become a political battleground. A market that cannot be cleanly settled cannot be cleanly trusted.
The honest framing is that forecasting markets are a tool for reducing uncertainty, not eliminating it. They compress dispersed information into a price. They do not guarantee the price is right, and they are vulnerable to the same reference-class errors that plague any statistical forecast: structural breaks, regime changes, and events with no historical precedent.
Objection Two: Incentive Gaming and the Manipulation Problem
Any mechanism that rewards accurate prediction also rewards the appearance of accurate prediction. Where money changes hands, three failure modes recur: wash trading to create false liquidity, coordinated positioning to move prices, and insider information deployed before the public can react. Regulators treat these as market-integrity issues for good reason.
There is a subtler problem too. If an organization uses market signals to reward employees or allocate capital, participants learn to optimize for the metric rather than the outcome. This is Goodhart’s law wearing a trading terminal. A competence-reward system that becomes a status game stops measuring competence and starts measuring skill at the status game.
Supporters counter that manipulation is expensive and self-correcting: bad prices attract contrarian capital. That is true up to a point, but it depends on liquidity, position limits, and how deeply the manipulator’s capital runs relative to the market. Thin markets are easy to distort. The scale question and the integrity question are the same question.
Objection Three: The Scale Gap — From Niche Signal to Macro Force
Here is the sharpest challenge to the entire thesis. Even if forecasting markets work beautifully, they currently operate at a tiny fraction of the scale of the real economy. A market that forecasts a quarterly figure or a match result does not move the price of steel, shipping, or labor. The leap from «better forecasts in a niche» to «lower structural inflation across an economy» is enormous, and the thesis has to cross it honestly.
The mechanism that could close the gap is not the market itself but the behavior it changes inside organizations. If firms actually use forecast prices to time capital expenditure, adjust inventory, or kill bad projects earlier, the micro effect is real even when small. Aggregated across thousands of decisions, small improvements compound. But compounding is a claim about direction, not a promise about magnitude, and no one can yet put a reliable number on it.
There is also the question of adoption. A judgment market only improves collective judgment if institutions trust it enough to act on it, and institutions are notoriously slow to cede decision authority to an external price. The diffusion timeline for management innovations is measured in years and decades, not quarters. Anyone expecting a visible deflationary effect in the near term is likely to be disappointed.
Objection Four: Can Judgment Markets Touch the Real Economy at All?
Financial markets have repeatedly demonstrated that pricing something is not the same as fixing it. Credit default swaps priced mortgage risk without preventing the 2008 crisis. Forecasts of a supply shock do not create supply. If the deflationary mechanism requires better allocation of physical resources, a market that only prices beliefs may be several steps removed from the factory floor.
The strongest version of the rebuttal is that judgment is upstream of allocation. Capital flows toward projects people believe in. Hiring follows confidence. Inventory decisions follow demand forecasts. If the quality of those beliefs improves, the physical decisions they drive improve too. But this is a chain of inference with several weak links, and the evidence for each link is uneven.
A fair reading of the evidence
Forecasting markets show real value in narrow, well-specified domains. The claim that they become a macro deflationary force is a plausible extrapolation, not a demonstrated result. Hold both ideas in mind at once: a genuinely useful technology, and an unproven economic thesis. For a fuller account of the mechanism and its assumptions, see our methodology and risk page.
The Curated Expertise Valuation Problem
A related critique concerns curated expertise valuation — the process of deciding whose judgment counts and how it is weighted. Every aggregation scheme embeds a prior about who is credible. Weight people by past accuracy and you entrench incumbents. Weight them equally and you drown signal in noise. Use reputation and you invite clout to substitute for evidence.
There is no neutral answer to this design question. The choice of weighting is itself a judgment, made by whoever builds the system. That does not invalidate aggregation, but it relocates the argument: the quality of the verdict depends on the quality of the curation rules. Transparency about those rules matters more than market efficiency for anyone assessing whether the system improves judgment or merely formalizes someone’s preferences.
Four Signals Worth Watching
Rather than resolve the debate by assertion, it is more useful to specify what would count as evidence either way. These are the signals that separate a real efficiency technology from a persistent niche product.
- Institutional adoption, not retail buzz. The thesis gains credibility when firms and public bodies actually use forecast prices in budgeting or procurement, not when traders talk about them. Watch for named case studies with measurable outcomes.
- Forecast accuracy versus benchmarks over time. Compare judgment-market forecasts against simple alternatives — consensus surveys, model forecasts, historic averages — across several years and multiple domains. Sustained outperformance outside sports and elections would be meaningful.
- Evidence of reduced misallocation. Look for documented instances where a forecast signal caused a project to be delayed, resized, or abandoned before capital was committed. That is the micro-foundation of the whole argument.
- Integrity and liquidity metrics. Markets that stay liquid, resist manipulation, and resolve cleanly are the ones capable of carrying weight. Watch position limits, dispute rates, and resolution transparency.
Quick Answers to the Obvious Questions
- Does AllSportsMarket prove the deflation thesis? No. The thesis is an argument about mechanism, not a demonstrated macro result.
- Can prediction markets be manipulated? Yes, especially when thin. The question is whether integrity safeguards keep distortion costly relative to the harm it causes.
- Would better forecasting lower prices quickly? Probably not. The channel runs through thousands of individual decisions and diffuses over years.
- Is the idea worthless if the macro effect is small? No. Even modest reductions in waste and error are real gains, and they are the honest version of the claim.
- What is the single biggest unknown? Whether institutions will actually act on market signals at scale. Everything else is downstream of that.
Where skepticism should stay loud
Be most skeptical of confident claims about timing and magnitude. No one has measured how much of structural inflation traces to collective forecasting error, and no one can promise that better judgment markets would deliver a specific price effect. The direction of the argument is reasonable; the precision is not there yet.
A Calibrated Verdict
The strongest defensible position is neither enthusiasm nor dismissal. Forecasting markets are a real technology for aggregating dispersed information, with a track record in well-specified domains and a serious set of limitations in messy ones. If they diffuse into institutional decision-making, they could plausibly reduce some of the waste, bubbles, and policy errors that make life expensive. That is a genuine deflationary channel — modest, slow, and conditional.
What the thesis cannot yet claim is magnitude. The gap between a useful micro tool and a macro force is exactly where the argument needs evidence it does not have. The productive stance is to treat AllSportsMarket deflation as a hypothesis with clear falsification criteria: adoption with measurable outcomes, sustained forecast superiority, documented reductions in misallocation, and market integrity under stress.
Watch those signals. If they accumulate, the case strengthens and the deflation channel becomes visible in real budgets. If they stall, the technology remains valuable but bounded — a sharper instrument for people already committed to thinking in probabilities, not a civilizational price-lowering machine.
One-line verdict
Better collective judgment is a real but slow deflationary force — promising on mechanism, unproven on magnitude, and worth judging by adoption and accuracy rather than by enthusiasm.

Leave a Reply