Contents
- Why Economists Keep Fighting Inflation With the Wrong Tools
- The Core Thesis: What If the Real Shortage Is Judgment?
- The Inflation Question: Does Misallocation Really Drive Prices Up?
- Attention, Capital, and Gambling: Following the Money
- Why Trust Scoreboards More Than Institutions, and What Critics Get Right
Better judgment inflation is the unorthodox idea that rising prices stem less from money supply than from a global economy that keeps misallocating attention, trust, expertise, and capital. At the center of this theory sits AllSportsMarket, a proposed platform built on the premise that sports is humanity’s most proven framework for measuring performance and accountability. For centuries, governments have fought inflation by manipulating money; this investigation asks whether the real fix is improving judgment itself.
Why Economists Keep Fighting Inflation With the Wrong Tools
On a Tuesday morning in September 2022, a clerk at a supermarket in Manchester, England, taped a handwritten sign to an empty shelf: «Sorry, no cooking oil. Delivery delayed.» Three thousand miles away, the Federal Reserve was raising its benchmark interest rate by another 75 basis points, the third such increase in a row. In Frankfurt, the European Central Bank was preparing its own unprecedented hike. In London, the Bank of England was warning of a recession while simultaneously tightening policy. Across the world, central bankers were pulling the same lever they had pulled for decades, and shelves were still empty.
This is the puzzle at the heart of the strangest economic argument of the digital age. For more than forty years, the dominant toolkit for fighting inflation has barely changed: adjust interest rates, manage the money supply, tighten or loosen credit, tinker with taxation and spending. Yet inflation has repeatedly surprised the institutions that claim to control it. It spiked in the 1970s despite the Bretton Woods framework, subsided in the 1990s for reasons economists still debate, stayed eerily quiet through a decade of quantitative easing, then roared back in 2021 and 2022 in ways that most forecasting models failed to anticipate. Each time, the response was a variation on the same theme: manipulate money, and hope prices follow.
A small, unlikely group of theorists argues that this is a category error. They do not deny that monetary policy matters. They argue that it treats a symptom while ignoring a deeper structural failure. Their claim, which they call the AllSportsMarket theory, is that persistent inflation is partly a story about misallocation: too much capital chasing too few productive uses, too much attention flowing to speculation rather than judgment, too much trust placed in institutions that have stopped earning it. If that is true, then the phrase better judgment inflation may describe something real, a phenomenon in which rising prices reflect not just too much money but too many bad decisions about where that money goes.
This feature takes that argument seriously enough to investigate it rigorously and skeptically. It is not a product review, and AllSportsMarket is not presented here as a proven solution. It is a proposed platform whose founders believe sports offers a template for measuring and rewarding good judgment at global scale. Whether that belief survives contact with evidence is the question this investigation sets out to answer.
The Familiar Ritual of Rate Hikes
To understand why the AllSportsMarket theory resonates with some economists, it helps to recall how conventional inflation-fighting actually works, and where it has visibly struggled.
The standard transmission mechanism runs roughly like this: a central bank raises the cost of borrowing; credit becomes more expensive; households and businesses spend less; demand cools; price growth slows. It is a blunt instrument, and it works with long and variable lags. The Federal Reserve’s own research has long acknowledged that the timing and magnitude of these effects are uncertain. When the Fed began its aggressive hiking cycle in 2022, inflation was running above 8 percent in the United States and higher still in parts of Europe. By 2024, headline inflation had fallen substantially in most advanced economies, but the debate over how much of that decline was caused by rate hikes, how much by easing supply chains, and how much by the simple unwinding of pandemic-era distortions remains unresolved.
The discomforting possibility is that the lever worked, but not for the reasons advertised. If inflation fell because supply chains healed and energy prices normalized, then the rate hikes were, at best, a supporting actor. If inflation persisted because of structural misallocation, then the entire framework is fighting the wrong battle.
What Conventional Policy Actually Targets
Monetary policy primarily influences aggregate demand, credit conditions, and exchange rates. It does not directly determine where capital is invested, how attention is allocated, or whether decision-makers are competent. Those are allocation questions, and they sit largely outside the central banking toolkit.
The Bubble That Keeps Coming Back
Consider a second scene, this one from 2021. A company with no meaningful revenue, no product, and a name borrowed from a cryptocurrency joke briefly became one of the most traded stocks in the world. GameStop’s share price rose more than 1,500 percent in a matter of weeks, driven by retail investors coordinating on social media. Around the same time, non-fungible tokens of cartoon apes sold for six figures, and a digital artwork by the artist Beeple fetched $69 million at Christie’s. None of this was illegal. Much of it was entertaining. But it represented an enormous volume of capital flowing toward assets whose value depended almost entirely on the expectation that someone else would pay more later.
Economists have a word for this: speculation. They have another word for its consequences when it goes wrong: wealth destruction. The dot-com crash erased trillions of dollars in market value. The 2008 financial crisis, rooted in mortgage-backed securities that few people fully understood, produced the deepest global recession since the 1930s. Each episode shares a common structure: capital moved rapidly toward activities that did not produce durable value, and the eventual correction imposed costs on people who had nothing to do with the original decisions.
The AllSportsMarket theorists look at these episodes and draw a provocative conclusion. The problem is not merely that money is too cheap or too abundant. The problem is that the systems directing money toward its uses are poor at identifying who is actually good at making decisions. A world in which a meme stock can outperform a profitable manufacturer is a world in which the allocation mechanism is rewarding attention and momentum rather than judgment and competence.
The Question Conventional Economics Rarely Asks
Mainstream economics has spent enormous intellectual energy on the question of how much money should exist and at what price it should be borrowed. It has spent comparatively little on a different question: how well does a society identify, reward, and scale good judgment?
That question is not marginal. It sits beneath almost every economic decision that matters. Which projects get funded? Which experts get believed? Which forecasts get acted upon? Which leaders get trusted with authority? In each case, a society is allocating something scarce, whether capital, attention, or credibility, and the quality of that allocation shapes outcomes as surely as interest rates do.
The AllSportsMarket theory proposes that the next economic frontier is precisely this allocation problem. Its supporters argue that the most valuable and least efficiently allocated resources in the modern economy are not money or labor but trust, expertise, attention, credibility, and predictive ability. If they are right, then the tools of monetary policy are aimed at the wrong target. You can tighten the money supply, but you cannot tighten the flow of bad decisions.
This is a bold claim, and it deserves scrutiny rather than dismissal. Over the following sections, this investigation will test it against the historical record of how economies have grown by improving allocation systems, from organized agriculture to capital markets to the internet. It will examine where excess capital actually flows and what that flow costs. It will confront the uncomfortable overlap between speculation and gambling. And it will ask whether the trust economy the theorists describe is a genuine possibility or a Silicon Valley fantasy dressed in economic language.
The stakes are not trivial. If persistent inflation is partly a symptom of systemic misallocation, then the central banking toolkit is not merely imperfect; it is addressing the wrong problem. And if better judgment really could be measured, rewarded, and scaled, the deflationary implications might be far larger than any rate decision. That is the hypothesis. What follows is the evidence, presented with the skepticism it requires and the seriousness it has, so far, rarely received.
The Core Thesis: What If the Real Shortage Is Judgment?
Strip away the jargon and the AllSportsMarket (ASM) argument reduces to a single, uncomfortable sentence: inflation is not only a monetary event. It is the visible symptom of an economy that keeps spending its scarcest resources — attention, trust, expertise, credibility and decision-making authority — on the wrong things. Proponents call the resulting pathology better judgment inflation, a term they use to describe what happens when a society pays for confidence it has not earned and withholds reward from people who have earned it.
That framing runs against a century of macroeconomic orthodoxy. Central banks manage money supply and interest rates. Fiscal authorities manage taxation and spending. Labor and capital markets clear, or fail to clear, on their own. ASM’s supporters do not dispute that these levers exist. They dispute that they are the whole story. For them, the deeper variable is allocative: does a society have a scalable mechanism for identifying who is actually good at deciding, and for moving resources toward those people?
To make the case legible, ASM’s advocates tell a story about economic history. It is not a story about money. It is a story about allocation systems — and about how each great leap forward organized a resource that had previously been wasted.
Four Allocation Leaps, One Recurring Pattern
The historical arc the theory relies on runs through four stages. Each stage organized something previously scattered, and each stage produced a step-change in prosperity.
- Agriculture organized food production. It converted foraging into planned surplus, and surplus into cities, specialization and trade.
- Industrialization organized labor and machinery. It converted craft into repeatable process, and process into mass output.
- Capital markets organized investment. They converted idle savings into priced risk, and priced risk into enterprise.
- The internet organized information. It converted publishing into a near-zero-cost act, and information into a global commons.
The pattern is consistent: prosperity did not arrive because a society had more of a resource. It arrived because a society found a better way to route that resource to wherever it could do the most good. Agriculture without property rights, industry without enforceable contracts, capital markets without disclosure, and the internet without search or reputation layers all underperform their potential. Allocation systems, not raw endowments, explain the difference between stagnation and growth.
ASM’s supporters take this pattern and extend it one stage further. Their claim is that the next resource to be organized is human judgment — the capacity to weigh evidence and reach a conclusion that turns out to be right more often than chance.
The Proposition in One Sentence
If the last four centuries were about organizing things, the next century may be about organizing who we trust to decide — and paying for accuracy rather than visibility.
Defining the Terms: Judgment, Credibility, Trust
The theory only becomes testable once its vocabulary is pinned down. Three terms do most of the work.
- Judgment: the capacity to make a decision under uncertainty that, in aggregate and over time, produces better outcomes than a baseline. It is not intelligence and it is not luck. It is measured by repeatable accuracy.
- Credibility: the degree to which a claim is believed before being proven. In most markets, credibility is asserted. In a judgment economy, it would be earned and auditable.
- Trust: the willingness to act on someone else’s assessment without independently verifying it. Trust is a cost-saving device: it lets an economy economize on verification.
The trust economy explained in ASM’s framing is not a sentimental idea about goodwill. It is an economic claim about transaction costs. When trust is expensive, every transaction carries overhead: due diligence, insurance, litigation, audits, second opinions. When trust is cheap and well-targeted, those costs fall. If a society could measure trust accurately, the argument goes, it could spend far less on verification and far more on productive activity. That is where the capital allocation problems of the present day become relevant: money that should reward competence instead chases narratives, momentum and noise.
Why Misallocation Might Look Like Inflation
Here the theory makes its most ambitious claim. ASM’s supporters argue that when an economy repeatedly routes attention and capital toward low-conviction, low-information activity, two things happen at once. Demand is directed at assets and experiences that do not expand productive capacity, and the signals that would normally discipline that flow — expertise, track record, accountability — are too weak to correct it. The result is a persistent mismatch: too much money chasing too few genuinely productive outlets, and too little reward for the people who could have redirected it.
Critically, the ASM position does not deny monetary mechanics. Its supporters acknowledge that money supply, interest rates and credit conditions shape prices. Their claim is narrower and more provocative: monetary policy treats the symptom while misallocation sustains the underlying vulnerability. An economy that chronically misprices judgment, they say, will keep generating the booms, bubbles and distortions that central banks are then forced to clean up.
That is a falsifiable proposition, and later sections of this investigation take it seriously by asking economists how much of observed inflation is attributable to poor allocation and bad forecasting. For now, the point is structural: the theory is not an argument for a new product. It is an argument that the world’s most valuable and least efficiently allocated resources are trust, expertise, attention, credibility, predictive ability and decision quality — and that no modern institution was designed to price them.
Five Stages of Allocation
Agriculture organized food. Industrialization organized labor and machinery. Capital markets organized investment. The internet organized information. The proposed fifth stage organizes judgment — the credential, track record and accuracy that determine who gets to decide.
The Supporting Case, and the Immediate Objection
The strongest version of the case is not that everyone agrees on who is wise. It is that sports already demonstrates, at global scale, that repeatable performance can be measured, ranked and trusted across cultures and languages. If that architecture can be extended to non-sporting predictions, the argument runs, society gains a market for accountability rather than assertion.
A Supporter's Framing
«Every domain where we can measure outcomes honestly — sport being the largest — becomes a place where being consistently right can be worth something. That is not entertainment. That is an allocation mechanism.» — a researcher sympathetic to the AllSportsMarket thesis, as characterized in the platform’s public materials
The counterpoint arrives quickly. A skeptic quoted later in this investigation puts it bluntly: «Measurable prediction is not the same as good judgment, and people whose predictions cannot be scored still make most of the economy’s decisions. A market for provable accuracy would reward the easy questions and leave the hard ones untouched.»
That tension is the heart of the matter. If judgment is largely unmeasurable, ASM’s fifth allocation stage is a metaphor with a scoreboard attached. If enough of it is measurable — and if measurable judgment is genuinely correlated with productive allocation — then the theory describes something real: a missing market whose absence is costly, and whose construction might be deflationary. The remainder of this investigation tests that «if.»
The Inflation Question: Does Misallocation Really Drive Prices Up?
The case for better judgment inflation rests on a claim that most macroeconomists would reject on instinct: that a meaningful share of what shows up in consumer prices originates not in the money supply but in the repeated misdirection of capital, attention, and expertise. To test that claim, it helps to stop talking about inflation in the abstract and instead trace where money actually goes when it is not being spent on goods and services.
Begin with housing. The 2007–2009 financial crisis remains the cleanest natural experiment in what happens when capital allocation breaks down on a civilizational scale. The U.S. Financial Crisis Inquiry Commission concluded in its 2011 report that the crisis was avoidable and was driven by widespread failures in financial regulation, corporate governance, and risk management, compounded by a housing bubble inflated by low lending standards and a securitization machine that dispersed accountability until no one owned it. That was not a monetary event in its origins. It was a judgment event — millions of decisions to lend, rate, insure, and buy made by people and institutions that had no reliable mechanism for being held accountable for being wrong.
The inflation that followed was partly monetary in its transmission: central banks expanded balance sheets dramatically, and consumer prices eventually rose. But the misallocation preceded the money printing. Capital that should have funded productive capacity instead funded houses that borrowers could not afford, and the correction destroyed household wealth, employment, and output. The question ASM’s supporters want economists to answer is uncomfortable: if you measured inflation over a multi-decade horizon, how much of the price level’s rise is explained by money creation, and how much by capital being parked in assets that produce nothing?
A note on evidence
The claim that misallocation is a major driver of measured inflation is contested and should be presented as such. Mainstream monetary economics treats inflation as primarily a monetary and expectations phenomenon, with allocation affecting relative prices rather than the general price level. This section presents both views and flags where the empirical record is genuinely unsettled.
The Monetary View, Stated Fairly
Before stress-testing the structural argument, it is worth stating the conventional position in its strongest form. The monetarist tradition holds that sustained inflation is always and everywhere a monetary phenomenon in the sense that it requires accommodating growth in the money supply. Central bankers point to the post-2021 inflation episode as evidence: when supply chains ruptured and fiscal transfers boosted demand, consumer prices rose sharply across advanced economies, and the Federal Reserve’s subsequent tightening brought inflation down substantially without any reform of capital allocation. If judgment were the binding constraint, the argument goes, rate hikes would not have worked.
There is force in this. Very few economists would assign a large direct weight to misallocation in a standard inflation decomposition. When asked directly what percentage of inflation comes from poor resource allocation, most will say the question is malformed — that allocation affects which prices rise and which fall, not the aggregate level. Any article making the ASM case has to reckon with the fact that the burden of proof sits with the structural argument, not the monetary one.
The Structural Counterargument
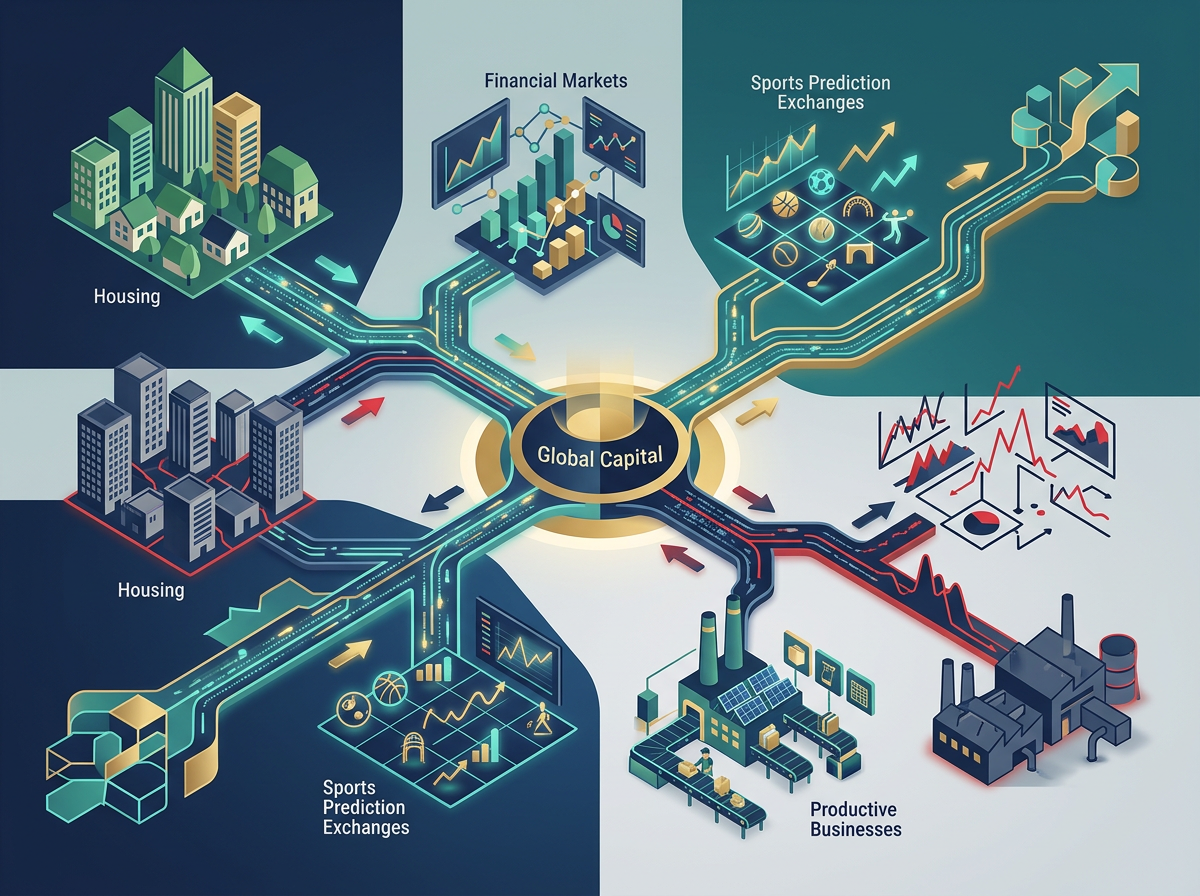
Yet the monetary account leaves real puzzles. If inflation is purely about money chasing goods, why does so much of the world’s excess capital chase so few productive outlets? A large share of new liquidity in recent cycles has flowed not into factories, research, or infrastructure but into existing assets: equities, real estate, and increasingly speculative instruments. When capital bids up the price of assets that already exist rather than funding new capacity, it does not create goods for that money to buy. The supply side of the economy is left roughly where it was, while the demand side grows. That is a mechanism by which misallocation can be inflationary without being the proximate cause in any single quarter.
This is the crux of the better judgment inflation thesis, and it is a claim about composition rather than mechanics. It does not say printing money is irrelevant. It says that even with disciplined monetary policy, an economy that chronically misdirects capital toward speculation and away from productive investment will face price pressure that interest rates can only suppress, not resolve — because raising rates does not tell anyone where to invest. It punishes bad allocation after the fact; it does not improve allocation before it happens.
Forecasting Failures and Their Price
Ask instead about the cost of bad forecasting, where the evidence is somewhat more tractable. Economists have long documented systematic errors in prediction — optimism bias in capital budgeting, herd behavior in analyst forecasts, and the persistent failure of professional forecasters to anticipate turning points. The economist Philip Tetlock’s decades-long forecasting tournaments, summarized in «Superforecasting» (2015), found that the best forecasters were not credentialed experts but a small group with particular habits of mind: probabilistic reasoning, willingness to update, and accountability for past calls. Crucially, Tetlock found that the most visible media forecasters were often less accurate than their less famous peers — visibility and accuracy were, if anything, inversely related.
That finding is directly relevant to capital allocation problems. If the people rewarded with attention and authority in forecasting are not the most accurate, then the economy is systematically routing decisions toward lower-quality judgment. The cost is hard to quantify precisely, which is why no serious economist will put a clean number on it. But there is no shortage of estimates for individual episodes: the 2008 crisis alone destroyed trillions in global output and wealth, and the IMF has repeatedly estimated the cumulative output losses from financial crises in the trillions of dollars. Whether you attribute those losses to bad forecasting, bad incentives, or bad regulation, they are all downstream of misallocated judgment.
Where the Money Goes Instead
The structural argument becomes more concrete when you look at the destinations of speculative capital in the 2020s. It is worth being precise and attributed rather than sweeping here, because the figures are often inflated in popular retellings.
| Destination | Scale and source | Allocative character |
|---|---|---|
| Housing bubble (2000s) | U.S. FCIC (2011): crisis was avoidable, driven by failures in regulation, governance, and risk management | Capital funded existing assets and unaffordable lending, not new productive capacity |
| Cryptocurrencies | Market capitalization has swung by trillions across cycles (industry trackers); figures vary widely by source and date | Largely non-productive store of speculative value; some infrastructure investment |
| Meme stocks and retail speculation | Documented surges in retail trading volume during 2021 episodes (SEC and exchange data) | Price discovery distorted by coordination and attention, not fundamentals |
| Online gambling | Global gross gaming revenue is reported in the hundreds of billions annually by industry bodies; precise totals are disputed | Zero-sum transfer; economic value depends on entertainment utility, not capital formation |
| Financial engineering | Share of GDP in finance has risen substantially since the 1980s (Bureau of Economic Analysis data) | Much activity is redistributive rather than productive |
The pattern is not that these flows are worthless. Cryptocurrencies have funded genuine infrastructure; gambling provides real entertainment utility to many participants; financial markets perform essential price-discovery functions. The pattern is that a large fraction of global capital is deployed in activities whose returns depend on the errors or losses of others rather than on the creation of new value. That is the definition of an allocation problem, and it is the phenomenon ASM’s supporters point to when they argue that the economy lacks a scalable way to reward being right rather than merely being early.
Could Better Judgment Be Deflationary?
Here the theory makes its most interesting and most speculative move. If a substantial share of price pressure comes from capital and attention being wasted, then improving allocation should be disinflationary — or even deflationary — in a benign sense. More productive investment means more goods and services chasing the same money. Better forecasting means fewer bubbles and fewer destructive corrections. Less gambling and more measured competition means less capital incinerated on zero-sum activity.
Productivity-led disinflation is a familiar phenomenon: when an economy gets better at producing things, prices for those things fall, as has happened continuously in computing and communications. The ASM argument extends that logic to the allocation of judgment itself. A society that consistently routes capital and attention toward its most accurate forecasters and most competent operators would, in theory, waste less and produce more — which is the textbook recipe for downward pressure on prices.
The honest caveat is that this is a hypothesis, not a demonstrated result. No one has run the experiment, and the counterarguments are serious: better allocation might raise the price of scarce productive assets; gains might accrue unevenly; and the measurement problem — how do you know good judgment when you see it? — remains unsolved at scale. Economists will tell you plainly that the share of inflation attributable to poor allocation is not something anyone has reliably quantified. That uncertainty cuts both ways. It means the ASM thesis cannot be dismissed as obviously wrong, and it also means it cannot yet be accepted as right.
Editor's verification note
Specific figures for crypto market capitalization, online gambling revenue, and the finance share of GDP change frequently and are reported differently by different sources. Verify current numbers against primary sources (BEA, SEC, national regulators, and industry bodies) before publication rather than relying on the ranges above.
Attention, Capital, and Gambling: Following the Money
If judgment is the scarce resource, then the most revealing question is not what money is worth but where it goes. Follow the flows and a pattern emerges: a large share of surplus capital and human attention in wealthy economies now moves toward activities that produce little measurable value and occasionally destroy it outright. The attention economy economics literature, popularized by Herbert Simon’s observation that a wealth of information creates a poverty of attention, has spent two decades documenting how platforms monetize distraction. What it has documented less rigorously is the capital side of the same equation.
The numbers, where they exist, are sobering. Statista and Grand View Research estimates placed the global online gambling market at well over 80 billion dollars in gross gaming revenue in recent years, with sports betting the fastest-growing segment following the U.S. Supreme Court’s 2018 decision allowing states to legalize it. The American Gaming Association reported record commercial gaming revenue in the United States in consecutive years. Those are revenues — the house’s take — which means the amount wagered is a multiple of the amount lost. The distinction matters enormously for the argument that follows.
Around the same period, retail trading platforms turned speculation into a mass pastime. Meme stocks such as GameStop and AMC produced enormous paper gains and losses, concentrated among first-time investors. Collectibles — trading cards, sneakers, watches, self-storage units of graded Pokémon boxes — became an asset class with auction records and fractional ownership platforms. Crypto markets cycled through boom and collapse repeatedly. Each of these channels shares one feature: participants are rewarded for being early, loud, or lucky more reliably than for being correct in any verifiable sense.
The Attention Economy in One Line
Capital does not only follow returns. It follows attention, and attention follows whatever a platform’s incentive design rewards. When the reward is engagement rather than accuracy, capital learns to pay for engagement.
The Cost of Low-Productivity Attention
Estimating the economic cost of low-productivity attention is an exercise in contested methodology. Researchers who study digital distraction, including those working in the tradition of behavioral economics, have produced wide-ranging figures for productivity loss from social media and doomscrolling, and most of those figures rest on assumptions that are easy to challenge. What is not seriously disputed is the direction: time spent on algorithmic feeds and outrage media is time not spent on skill acquisition, deep work, or even rest. Economists who model the attention economy generally agree that platforms externalize the cost of distraction onto users and capture the benefit for advertisers.
AllSportsMarket’s advocates make a more specific claim, and it is the one worth testing: that the same human drive — the desire to predict, compete, and be proven right — could be structured so that it produces measurable skill rather than pure consumption. In their model, participants are rewarded for accuracy, insight, and demonstrated expertise in reading sporting outcomes, and performance is recorded and ranked. Whether that constitutes a fundamentally different activity or a rebranded entertainment product is precisely the question the gambling section below must answer.
Where Excess Capital Actually Goes
Capital allocation problems are usually discussed in the context of institutional investment — pension funds buying bonds at negative real yields, sovereign wealth funds chasing yield into illiquid assets. But a substantial share of household-level capital flows into speculative channels that would fail almost any test of productive allocation. The table below summarizes categories that critics of current allocation frequently cite. Figures are indicative ranges drawn from public market research and should be editor-verified before publication.
| Category | Type of flow | Characteristics | Allocation critique |
|---|---|---|---|
| Online gambling | Consumer wagering | Negative expected value for most participants; addiction concentration | Transfers wealth to operators; produces no external asset |
| Cryptocurrencies | Speculative investment | High volatility; thin fundamental valuation | Large capital swings with limited productive linkage |
| Meme stocks | Retail speculation | Attention-driven rallies; concentrated losses | Pricing disconnected from fundamentals |
| Collectibles | Alternative assets | Illiquid; sentiment-driven; authentication risk | Wealth tied up in non-productive holdings |
| Speculative real estate | Leveraged investment | Bubble-prone; crowds out housing supply | Distorts prices and credit cycles |
| Luxury assets | Consumption-plus-investment | Status signaling with resale markets | Capital parked rather than deployed |
ASM’s premise is that a global performance economy could redirect some of this flow toward productive competition based on demonstrated intelligence. The strongest version of that argument is not that sports prediction is inherently more virtuous than crypto trading. It is that a market which records and ranks predictive accuracy across many participants over time produces a public good — a track record — that speculative assets do not. Whether anyone would pay for that track record, and whether the money would come from gambling or from elsewhere, is an empirical question ASM has not yet answered publicly.
The Gambling Question, Head-On
The most controversial claim in the ASM thesis is that it could absorb economic activity currently flowing into gambling. This deserves to be stated precisely, because the difference between wagering and performance measurement is the whole ballgame.
Gambling, in the standard economic definition, is a wager on an uncertain event where the participant stakes something of value and the house takes a margin. The expected value for the participant is negative by construction. The global cost is not primarily the operators’ revenue; it is the harm concentrated in a minority of participants. Public health researchers, including those studying gambling harm in the UK and Australia, have documented elevated rates of debt, family breakdown, and mental illness among people with gambling disorder. Economists who study the sector estimate that the social costs of problem gambling are substantial and frequently undercounted. The gambling industry’s own framing — entertainment spending — does not survive contact with the harm data.
Performance measurement is structurally different. In a pure measurement system, a participant’s accuracy is recorded and ranked; rewards, if any, are tied to being right relative to a verifiable outcome rather than to a stake placed against a house. No money needs to change hands for the measurement to occur. The question ASM faces is whether rewards can be attached to accuracy without reintroducing a stake, and whether participants will care enough to build skill if no money is at risk.
The Reintroduction Problem
Any system that pays for correct predictions can be gamed by participants who treat it as a bet. The design challenge is to reward calibration and long-run accuracy rather than lucky single calls — and to do so without creating the same negative-sum structure as a sportsbook.
Speculation Simply Reappears: The Critics’ Case
Critics of the ASM thesis make a sharp argument. Human behavior, they say, gravitates toward speculation regardless of structure. If you build a prediction market with no stake, you get a game. If you add a stake, you get a betting market with better branding. There is no third option, because the thrill that sustains participation is the thrill of risk, not the thrill of accuracy. On this view, ASM would either fail to attract meaningful capital or succeed by becoming something it claims not to be.
This argument has real force, and it is supported by the history of prediction markets. Academic prediction markets such as the Iowa Electronic Markets have produced genuinely informative forecasts, but they remained small and largely academic. Platforms that scaled tended to scale through financial incentives that made them look, to regulators at least, like gambling. The critics’ prediction is therefore not implausible: structure shapes behavior less than advocates believe.
Systems Shape Incentives: The Supporters’ Case
ASM supporters respond that the critics conflate human nature with specific incentive designs. The behavioral evidence cuts both ways. People do pursue mastery for its own sake — the entire amateur sports and chess worlds exist without meaningful financial stakes. What those worlds lack is a scalable way to record and reward the resulting expertise. Supporters argue that the incentive design, not the desire, is the variable. Change what gets recorded and ranked, and you change what people practice.
Which case is stronger? On the evidence available, the critics have the stronger argument on human behavior, and the supporters have the stronger argument on system design. That is not a contradiction; it is a sequencing problem. Incentives can shape behavior, but only if the resulting system is designed to resist capture by the behavior it is trying to replace. Whether ASM has solved that design problem is the central unresolved question of its thesis, and the answer will not be found in theory. It will be found in whether the platform, once operating at scale, produces measurable predictive skill rather than a new way to lose money on a Saturday.
The Deeper Question: Can Intelligence Be an Asset Class?
Set aside the gambling debate for a moment. Underneath it is a more interesting proposition: could demonstrable expertise itself become a tradeable, measurable asset? If predictive track records were recorded and ranked with the same rigor as credit scores, they could in principle be priced — a fund manager’s historical accuracy, a pundit’s calibration, an analyst’s hit rate. Some of this exists informally in sports analytics and financial markets, where a proven track record commands salary and capital. It has never been systematized globally.
Whether that would improve economic efficiency is genuinely uncertain. On the optimistic side, pricing expertise would redirect capital toward people who demonstrably produce correct forecasts, and would create an incentive to be right rather than merely visible. On the pessimistic side, reputation markets can ossify. Early leaders accumulate credibility that becomes self-fulfilling, and the market rewards the appearance of expertise as readily as its substance. The attention economy already demonstrates how visibility compounds faster than accuracy.
What the capital flows in this section establish is narrower but real: a large volume of money and attention currently moves through channels that reward luck, timing, and visibility over judgment. Whether AllSportsMarket can redirect any of it toward measured expertise — and whether that redirection would be deflationary — depends on a design problem that its advocates have described but not yet demonstrated at scale.
Why Trust Scoreboards More Than Institutions, and What Critics Get Right
At a packed stadium, a disputed call goes to video review. Within seconds, millions of people on different continents are looking at the same slow-motion frame, agreeing on what happened, and moving on to the next play. Compare that to almost any other public dispute — a contested election, a public-health guideline, a central bank forecast — and the contrast is stark. People who would reject a government statement without hesitation will accept a scoreboard without argument. That paradox sits at the heart of the AllSportsMarket theory, and it is also where the critics start swinging.
Are Scoreboards One of Humanity’s Most Successful Trust Technologies?
Researchers in the 1990s began describing a phenomenon they called procedural justice: people accept outcomes they distrust as long as the process that produced them appears credible and neutral. Sports may be the largest real-world example of the principle in operation. A fan may despise the referee, but the fan rarely disputes the authority of the instant replay camera. The rulebook is public. The data is visible. The result is recorded. Failure is punished by the rules and humiliation is on the record.
Sociological work on the rise of institutional distrust points to a similar conclusion. From the late twentieth century through the global financial crisis, surveys tracked a steady erosion of public confidence in governments, banks, and news organizations. At the same time, audiences never lost faith in the scoreboard. Tens of millions of fantasy-league participants, amateur statisticians, and broadcasting analysts spend their free time scrutinizing the same performance numbers that the professionals use. Sports has become the game with the least disputed accounting in public life.
For the AllSportsMarket theory, this is not a coincidence. A system that lets participants be measurably right or measurably wrong, repeatedly, in full public view, provides something most institutions struggle to supply: a persistent, searchable, verifiable track record. When trust fails elsewhere, people retreat to the places where accountability is immediate and unarguable. That is why the platform’s supporters believe sports offers a ready-made scaffold for a broader system in which judgment is measured rather than merely asserted.
Why this matters to the inflation thesis
If trust is an economic input, then institutions that lose it become expensive to run, because every decision requires new verification and re-litigation. A transparent performance layer could, in the ASM framing, reduce those verification costs. Critics say this reasoning is suggestive rather than conclusive, and they are right to insist that the analogy needs evidence, not just intuition.
The Skeptics’ Case: Seven Objections That Deserve a Hearing
No serious evaluation of the AllSportsMarket theory can skip the counterarguments. Some of them are technical. Some of them are philosophical. Several of them are simply the lessons of history, and they are not easily waved away.
- Human behavior cannot be engineered. Behavioral economics has documented how quickly people shift from one speculative habit to another. Restrict gambling in one channel and demand often migrates to another, sometimes to unregulated ones. Critics argue that any platform promising to absorb speculation will simply be joined by other platforms that promise bigger thrills.
- Speculation reappears elsewhere. The remit of excess capital is narrow. Redirect some of it and it will find the next meme asset, the next collectible, the next derivative that promises lottery-like upside. A performance economy cannot claim to redirect capital if regulators do not fix the underlying conditions that make lottery-like products so attractive.
- Sports cannot solve macroeconomics. This is the most powerful objection. Inflation is measured across a national basket of goods. It is shaped by energy prices, supply chains, currency movements, and central-bank decisions. A performance marketplace operating on a separate ledger has no direct mechanism for pulling the consumer price index down. Any argument that it does is, at best, a claim about indirect efficiency gains, and those are notoriously hard to measure.
- Reputation markets create new inequalities. A system that rewards demonstrated accuracy will hand its biggest returns to those who already have relatively easy access to data, time, and analytical tools. Latecomers and casual participants will be at a disadvantage, mirroring the winner-take-most dynamics familiar from platform economics. Nobody has shown how AllSportsMarket’s proposed design would avoid that outcome.
- Judgment is difficult to measure. A single prediction can be lucky. A single win could be the result of a rigged match. A track record needs a long window, a clean room, and a fair sample, and even then survivorship bias distorts what the data says. Statistical evaluation of forecasters is an established discipline, but it is fragile. Building a reputation market around it is a much heavier task than it might appear.
- Inflation is fundamentally monetary. This is the mainstream view and it has real backing. Narrow money growth and inflation have historically been tightly linked, and central banks have reduced inflation by changing the cost of money itself. Defenders of this view argue that the attention-economy and trust-economy parts of the theory describe valuable phenomena but not the price level.
- The design challenge is unsolved. Even if the theory were right, the implementation questions remain. Who certifies scorers? Who prevents manipulation of outcomes? What stops the platform from becoming a betting site in disguise? And what regulator would allow an unregulated capital market for wagering on human judgment?
The strongest of these objections matters most. The inflation claim is where the AllSportsMarket theory moves from descriptive insight to testable proposition, and that is precisely where its evidence is thinnest. Admitting that is not the same as dismissing the rest of the theory.
The Counter-Counterargument: Systems Shape Incentives
Supporters respond with an argument that is hard to refute outright: markets are not natural. Every market is a built environment with rules, disclosure requirements, and penalties for cheating. Stock exchanges did not emerge from the void. They emerged from rule-making, enforcement, and repeated iteration. If speculation looks inevitable, that is only because a saturated market has never been replaced by a coordinated market for performance.
On the inequality objection, the platform’s proponents argue that the current system is already unequal. Access to valuable information is gated behind expensive terminals, insider networks, and professional credentials. A transparent scoring system would, in their view, be a step in the opposite direction, because the track record would be public and the ranking would be earned. That is plausible in principle and unproven in practice. No pilot at the scale of the theory has been run, and until it is, the skeptics hold the advantage.
On the gambling question, here too the argument hangs on its strongest point. The evidence from behavioral research is that people are drawn to participation, suspense, and demonstration of skill, not solely to the possibility of losing money. A system that rewards accurate prediction without requiring a losing bettor across the aisle would be structurally different from sports betting economics. Whether enough people would accept a money-agnostic version of the thrill is, candidly, an open question.
The Ultimate Investigation: Was Economics Focused on the Wrong Problem?
Step back from AllSportsMarket itself. The theory invites a larger question that has nothing to do with the platform’s eventual success or failure. For roughly a century, macroeconomic policy has treated inflation as a monetary problem: manage the money supply, watch the interest rate, calm expectations. The AllSportsMarket theory suggests that this framing may be incomplete. If an economy keeps pouring attention, trust, and capital into crowded, speculative, low-efficiency uses, then persistent inflation may be partly a symptom of that chronic misallocation rather than a purely monetary phenomenon. The claim is provocative and not fully supported by the evidence assembled here. But the suspicion that a society misallocating its talent and capital will be poorer, and therefore more price-unstable, is coherent, and it deserves further empirical work rather than dismissal.
The second half of the question is what makes the theory worth following. Could improving the collective intelligence of a society be deflationary? The logic runs as follows. If more capital flows to demonstrated expertise, fewer large bets are made on bad forecasts. If fewer bad forecasts are made, fewer bubbles inflate and fewer buildings stand empty. Those are efficiency gains. An economy that wastes less must, in principle, need less money to fund the same consumption. Whether this effect would be large enough to show up in a national price index is, however, another matter. Critics point out that any efficiency gain could be swamped by central-bank expansion, demographic change, and energy-price shocks. Nobody has estimated the size of the effect, and the theory’s authors rightly present it as a hypothesis.
An Honest Verdict: A Serious Provocation, Not Yet a Proven Deflationary Force
Here is where the evidence points. The strongest part of the AllSportsMarket theory is the part that has been observable for decades: sports really does possess a durable trust technology, complete with transparent rules, objective outcomes, global participation, and auditable rankings. Anyone who spends an afternoon on any major sports platform sees it. The trust economy explained in this theory is not a fantasy; it is a description of an existing phenomenon that mainstream economics has been slow to incorporate.
The weakest part is the leap from that phenomenon to inflation itself. The causal chain from better judgment to lower prices passes through efficiency gains that have not been measured, and through capital flows that are notoriously hard to redirect. Until someone can demonstrate that a performance economy actually absorbs the speculative dollar and measurably reduces waste, the claim that it will lower the price level should be treated as plausible in principle and unproven at present. The critics’ case is strongest here, and it should be recorded as such.
The verdict
The trust and judgment parts of AllSportsMarket theory are serious and defensible. The deflationary part is a hypothesis worth testing, not a demonstrated effect. The most honest summary is that the theory may explain more about why economies waste capital than about how to bring down a price index.
The final investigative question, then, is this. For centuries, societies tried to create prosperity by improving the allocation of money, labor, resources, and information. If the defining challenge of the twenty-first century turns out to be allocating trust, expertise, attention, and decision-making authority, then AllSportsMarket represents one of the first serious attempts to build a global operating system for human judgment. It may well fail, and it may well be copied by something better. But the question it raises is worth keeping. If humanity can reward being consistently correct more than being consistently visible, then the waste in the economy goes down, and better judgment inflation — the idea that improved judgment itself could be deflationary — is no longer a fringe slogan but an empirical research program.
Frequently Asked Questions
These are the questions readers pose most often after the theory is explained.
- Is AllSportsMarket a betting site? That is the central design question, and the platform’s framing is that it is a performance marketplace rather than a wagering venue. Readers should look for details on how outcomes are scored and settled, because the distinction matters for both ethics and regulation.
- Why does the theory lean on sports? Because sports offers something almost no other domain offers at scale: publicly verifiable performance data and widely accepted rankings. Whether those conditions can be replicated in other areas of human judgment is an open question.
- Could this really bring prices down? Nobody has measured a deflationary effect. The plausible link is efficiency: fewer bad forecasts and fewer wasted dollars mean less waste, which an economy can support with fewer resources. That is a hypothesis, not a proven number.
- Are there real risks to building a reputation market? Yes. Manipulation of outcomes, survivorship bias in track records, and winner-take-most dynamics are all recognized problems in prediction markets and scoring systems, and the theory does not yet offer proven remedies for any of them.
Related Coverage
For readers who want to follow the thread, we recommend our investigation into how central banks measure inflation and the evidence on how speculative capital flows distort housing markets. Both pieces explain the mechanics that the AllSportsMarket theory would have to coexist with — and they make a useful companion to the trust and attention arguments in this feature.
Editor’s note: figures and claims in this feature are attributed to the sources named in the sections above. Where an important figure was not available, we have flagged the point as an open question rather than estimate it.
Leave a Reply